
National security analysts cannot afford to study adversaries solely through military capabilities; economic intelligence is often the earliest and most reliable indicator of strategic intent.
Trade flows, currency policy, debt exposure, energy dependencies, and capital movements reveal both vulnerabilities and ambitions long before they manifest as overt action. Failure to understand these signals invites strategic surprise, as history repeatedly demonstrates.
Equally critical is applying that same analytical rigor inward.
A nation that does not honestly assess its own fiscal trajectory, industrial base, and financial dependencies risks becoming blind to the very pressures it seeks to exploit in others.
Strategic awareness begins with external observation, but it is sustained through disciplined self-examination.
For the United States the real question is not whether the petrodollar is collapsing, but what a series of seemingly disconnected events now signals about its future:
This week alone, tensions in the Strait of Hormuz have again raised the risk of disruption to the world’s most critical oil chokepoint, while Gulf states are quietly recalibrating their positions, with the United Arab Emirates asserting greater independence from traditional oil cartel dynamics and Saudi Arabia hedging its strategic relationships.
At the same time, the BRICS bloc continues to expand its ambitions, building alternative payment systems and experimenting with non-dollar energy settlements, even as U.S. sanctions on Iran and Venezuela push more oil trade into shadow networks that deliberately bypass the formal dollar system.
Taken together, these developments are not isolated headlines; they are pressure points on a single system that has underwritten global trade and American power for decades, and they reveal a gradual shift from unquestioned dollar dominance to a more contested, multipolar financial order.
The question is not whether the petrodollar is dead.
It is not.
The real question is whether the system that made the dollar strength feel automatic is becoming more conditional, more political, and more expensive to defend.
That is the quiet strategic tension under the headlines about tariffs, the US dollar engine still feels automatic but is becoming more conditional, more political, and more expensive to defend.
That is the quiet strategic tension under the headlines about tariffs, the Gulf, Iran, China, Brazil, Russia, India, China, and South Africa - known as BRICS - and the United States national debt.
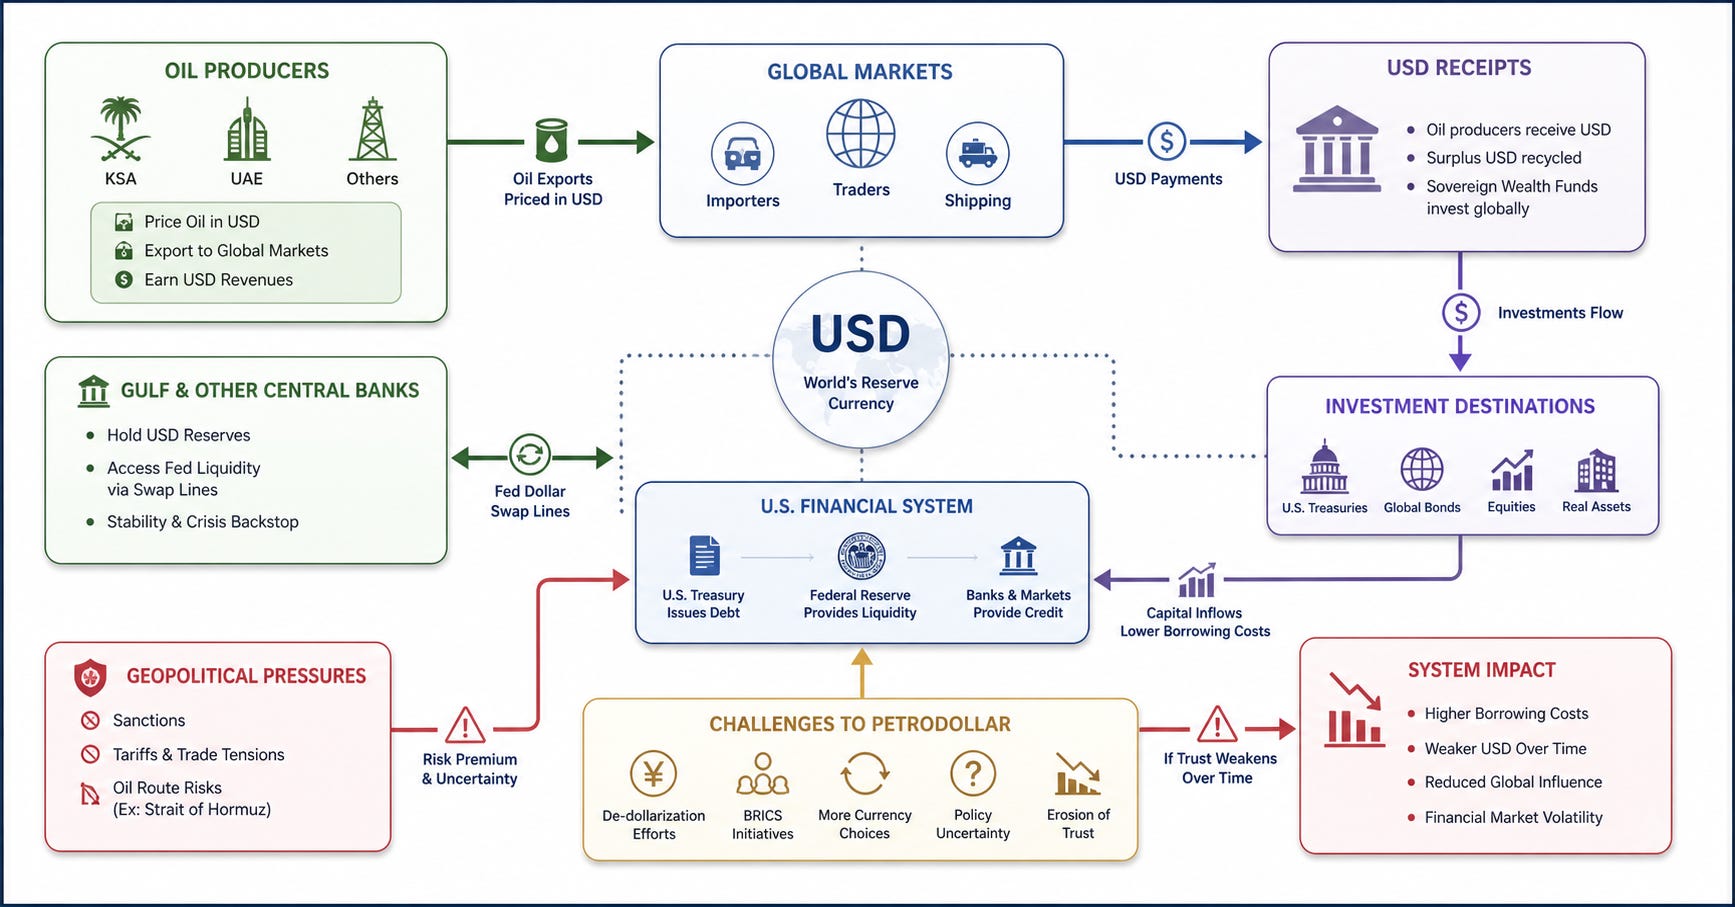
Start with the basic machine. The United States dollar is the world’s main reserve currency, which means governments, central banks, banks, companies, and investors hold it because they trust it, need it, and can use it almost everywhere.
The Money Printing Machine - Deficits be Damned
Oil matters because for decades the global oil trade has been heavily priced and settled in dollars. That created a circular system: countries need oil, oil is mostly paid for in dollars, so countries need dollars. Then many of those dollars need oil, oil is mostly paid for in dollars, so countries need dollars. Then many of those dollars return to the United States through purchases of United States Treasury securities, which are the government’s bills, notes, and bonds, coupled with Foreign Military Sales (FMS).
A self-licking Ice Cream Cone.
Oil as the Economic Lever
A Treasury security is an IOU from the United States government. When Washington spends more money than it collects in taxes, it borrows by selling these securities. The Treasury Department explains the national debt in exactly those terms: when spending exceeds revenue, a deficit results, and the government borrows by selling marketable securities such as Treasury bills, notes, and bonds. Treasury’s public debt data showed total public debt outstanding near $39 trillion at the end of April 2026. Debt to the Penny is not a slogan.
It is the daily scoreboard.
What we Claim Versus What We Do
Presidents often prefer a Federal Reserve chair aligned with their economic priorities because monetary policy - especially interest rates and liquidity - has immediate political and economic consequences. In Federal Reserve tradition, independence is designed to insulate decisions from short-term political pressure, but a president like Donald Trump has openly favored lower rates and more accommodative policy to support growth, markets, and fiscal flexibility.
As of late April 2026, President Donald Trump has nominated Kevin Warsh to replace Jerome Powell as chair of the Federal Reserve. The Senate Banking Committee advanced Warsh’s nomination on April 29, 2026, with a 13-11 party-line vote, setting the stage for a final, expected confirmation by the full Republican-controlled Senate to take over after May 15.
Seeking a hand-picked leader reflects a desire for tighter coordination between fiscal and monetary policy, though critics argue it risks undermining the credibility of an institution whose power depends on being seen as objective and not driven by political will.
The Treasury borrows.
Congress spends.
The Federal Reserve sets monetary policy, regulates parts of the banking system, and can create bank reserves to buy or lend against financial assets in a crisis.
That does not mean every dollar of debt is simply printed in a cartoon sense.
It means the United States has a unique privilege: it borrows in the currency it issues, while the world still needs that currency for trade, reserves, and crisis liquidity.
That privilege is why swap lines matter.
A swap line is a temporary currency exchange between central banks.
If a foreign central bank needs dollars in a panic, it can swap its own currency with the Federal Reserve and then lend those dollars into its domestic banking system. The Federal Reserve and the New York Federal Reserve say the standing dollar swap network includes the Bank of Canada, the Bank of England, the Bank of Japan, the European Central Bank, and the Swiss National Bank. Federal Reserve. New York Federal Reserve
But the leap from that fact to the claim that Gulf access would automatically lock sovereign wealth funds into Treasuries is too clean.
It is directionally plausible, not mechanically guaranteed.
If the United Arab Emirates, Saudi Arabia, Qatar, or other Gulf states received reliable dollar liquidity support in wartime, that would strengthen the dollar side of their balance sheets and reduce pressure to settle more trade in Chinese yuan.
Reuters reported that the United States was discussing dollar swap-line arrangements with Gulf and Asian partners, while the Atlantic Council cautioned that the public discussion has sometimes blurred the distinction between true Federal Reserve central bank swap lines and other United States-backed dollar support facilities. Reuters Atlantic Council
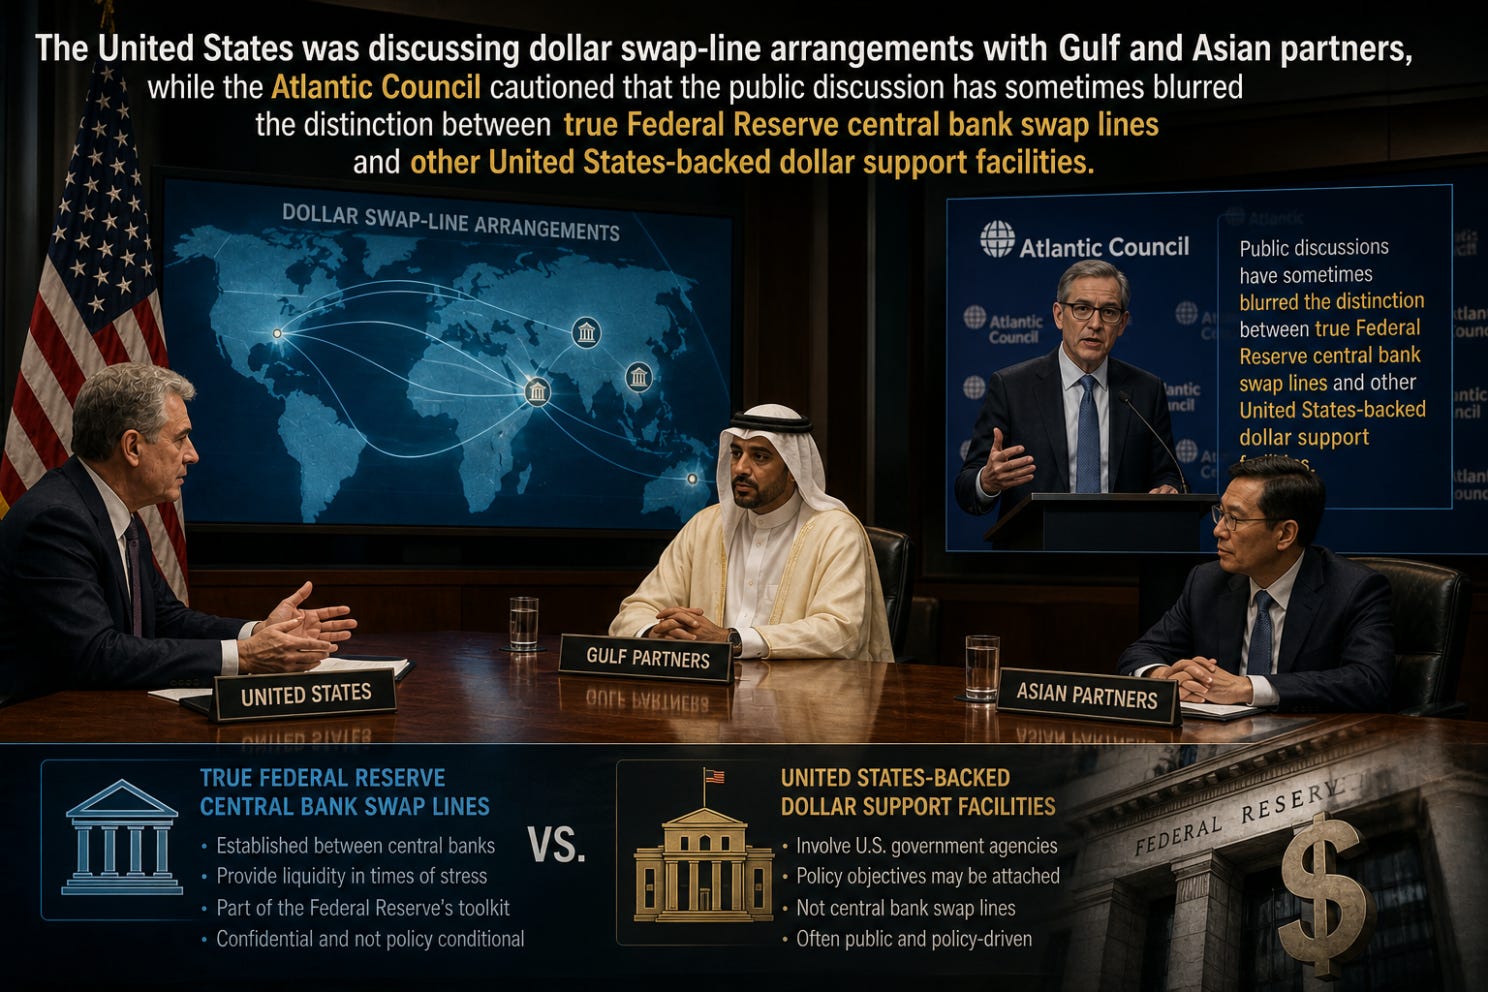
U.S. Dollar Swap Line Arrangements
Lets think like 9th graders
Pretend we are a high school class, think of it this way:
The dollar system is like the school’s main power grid.
Everyone complains about the electric company, but all the computers, lights, chargers, and doors still run through that grid.
China is building a generator.
BRICS is talking about a backup power system.
Iran is trying to run around the school’s billing office.
The Gulf states are buying batteries.
But when the building catches fire, everyone still wants the main grid to work.
The UAE Leaves OPEC!
The United Arab Emirates leaving the Organization of the Petroleum Exporting Countries, or OPEC, matters because it tells us the Gulf is no longer moving as one disciplined oil bloc. Reuters and the Associated Press reported that the UAE announced its withdrawal from OPEC effective, yesterday, May 1, 2026, after years of frustration over production quotas and a desire for more independent energy policy. Reuters Associated Press.
This does not mean Abu Dhabi is abandoning the dollar. It means Abu Dhabi wants more room to maneuver.
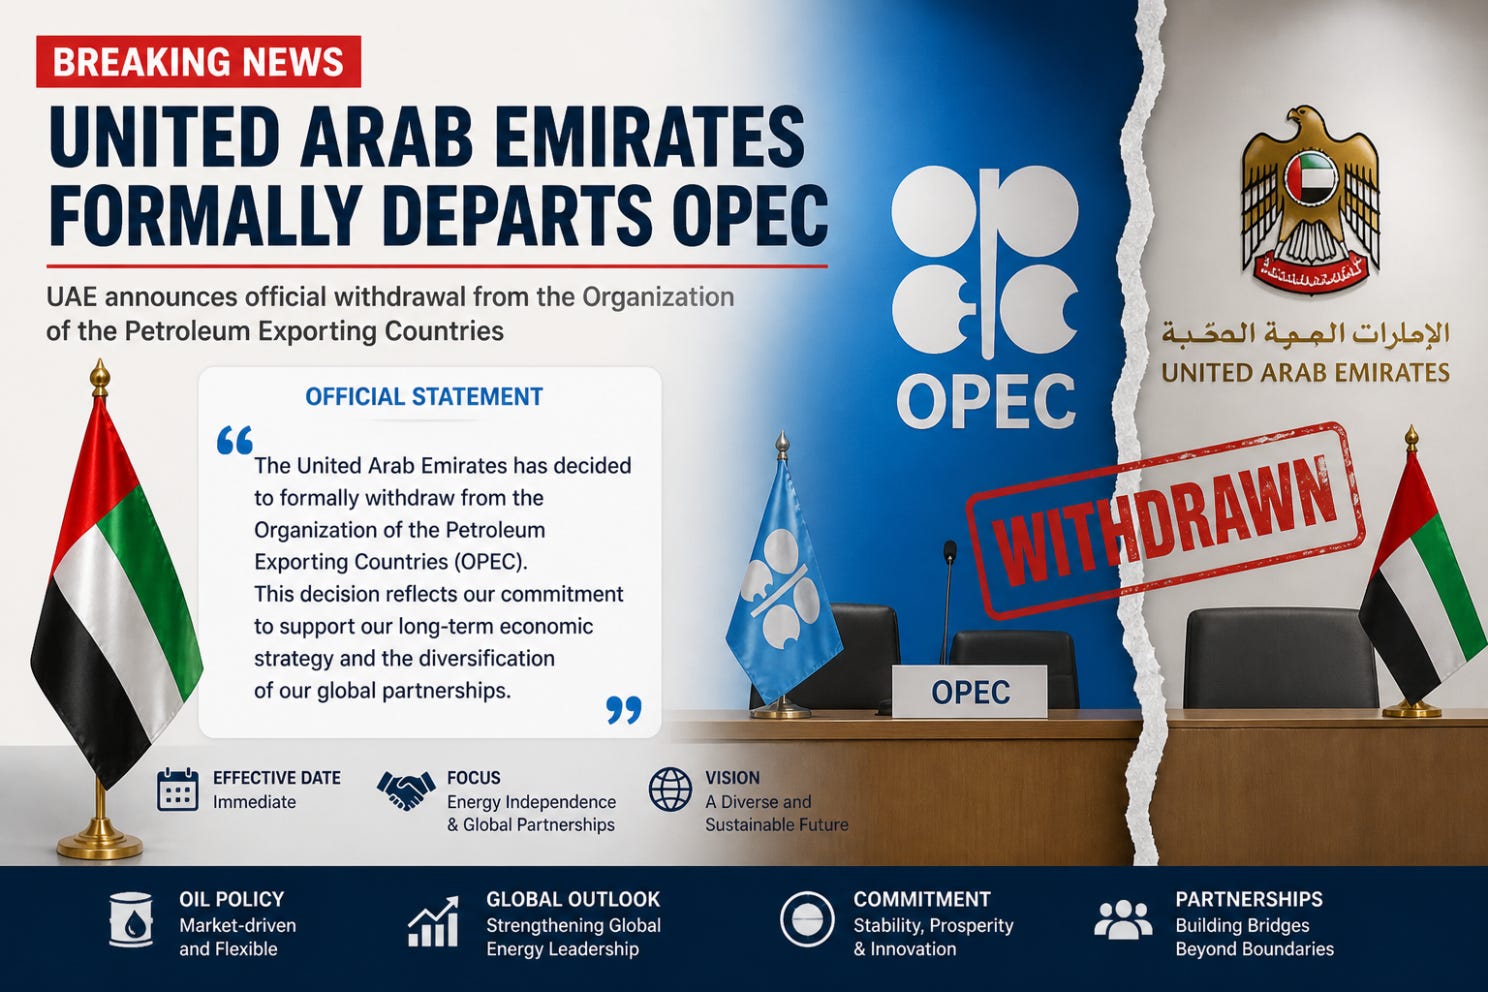
UAE Preserving its Options
That difference matters. Leaving OPEC weakens Saudi Arabia’s ability to manage supply discipline through the cartel.
It also gives the UAE more freedom to produce, sell, hedge, and negotiate energy arrangements according to its own national strategy.
In a world where China is the dominant buyer of Gulf energy and the United States is the dominant provider of security, finance, and dollar liquidity, the UAE is not choosing one side.
The UAE is a non-aligned nation.
It is increasing optionality.
Saudi Arabia is doing something similar, but through security policy. Reuters reported that Ukraine and Saudi Arabia signed a defense cooperation agreement focused on future contracts, technology collaboration, investment, air defense, and drone-related expertise. Reuters. Saudi Arabia did so without consulting the United States.
Previously, unthinkable. What changed? Insults.
A nation/state’s Number one Obligation: Insure its own survival
That is not just a military story. It is a signal that Gulf capitals no longer assume Washington alone can solve their missile and drone defense problem. After years of Iranian and proxy threats to energy infrastructure, Gulf leaders are shopping for battle-tested capabilities wherever they can find them.
Trump’s public language toward Mohammed bin Salman also matters because reserve-currency systems run on trust as much as arithmetic. Trump’s remark that the Saudi crown prince was effectively ‘kissing my ass’ may play as domestic political theater, but in palace politics it is heard as humiliation. reported by NDTV
Gulf rulers can tolerate hard bargaining. They do not like being publicly diminished. When the security guarantor becomes unpredictable, allies diversify their insurance.
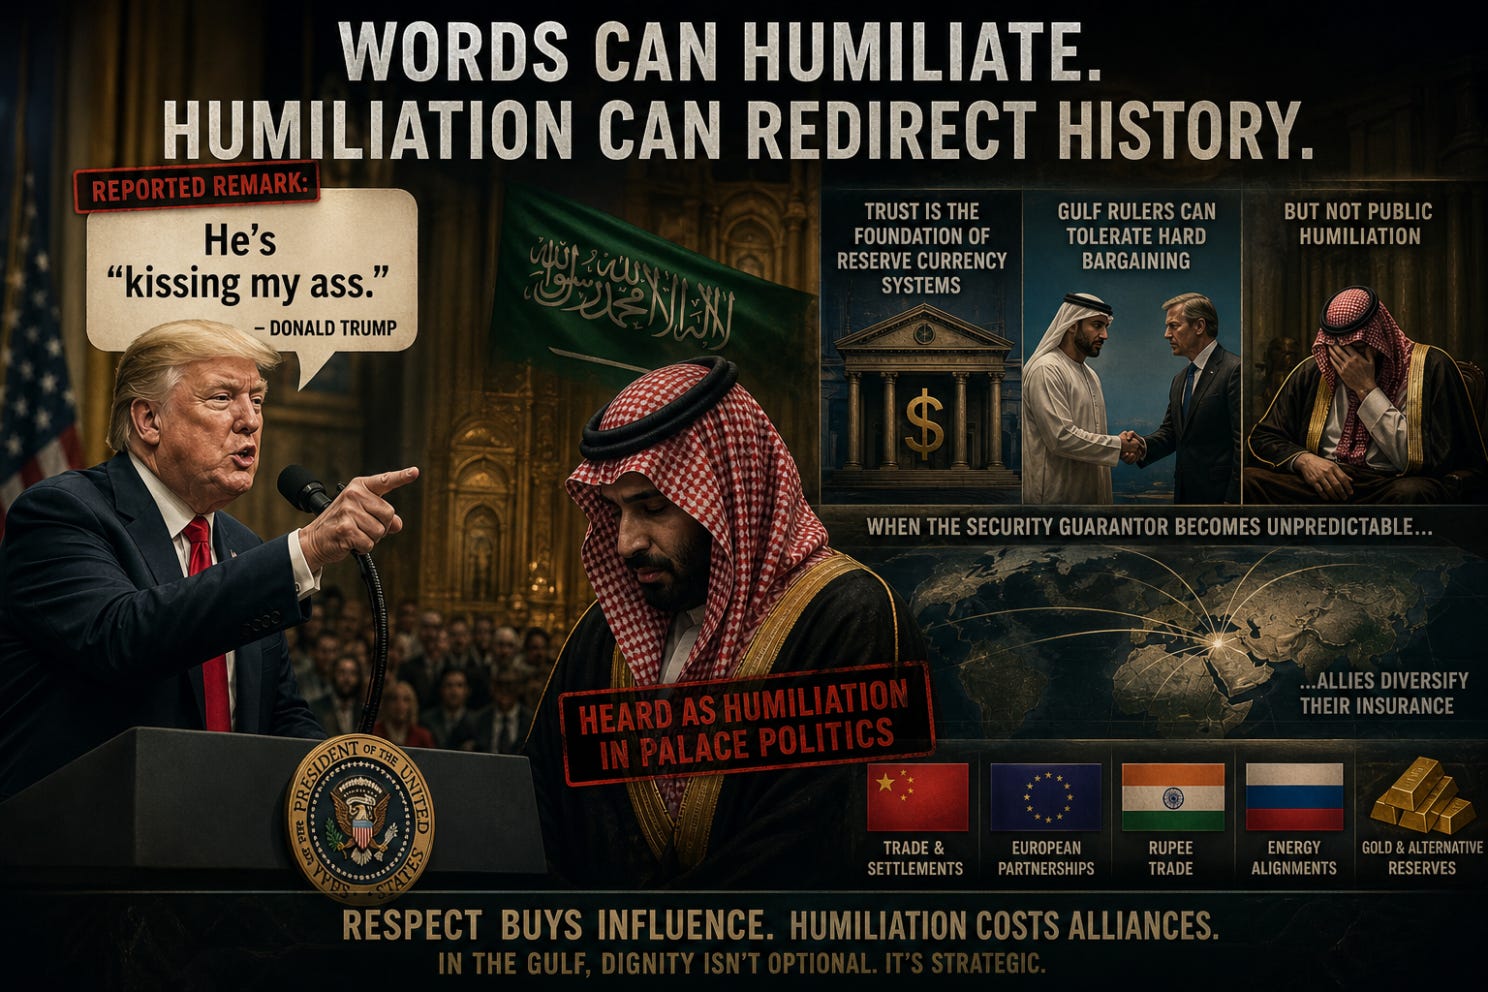
Respect Buys Influence - Humiliation Costs Alliances
Iran’s Strategy
Iran’s role is different. Iran does not need to defeat the United States Navy to create strategic effect. It only needs to make enforcement look costly, incomplete, or politically dangerous. It is doing just that. Reuters reported that the United States blockade forced several Iranian oil tankers back, while other reporting and maritime tracking described evasion techniques including fake flags, disabled tracking signals, shell companies, and routes hugging the Iranian coastline. Reuters Windward
This is the maritime version of shadow banking: hard to stop completely without escalating into a wider war.
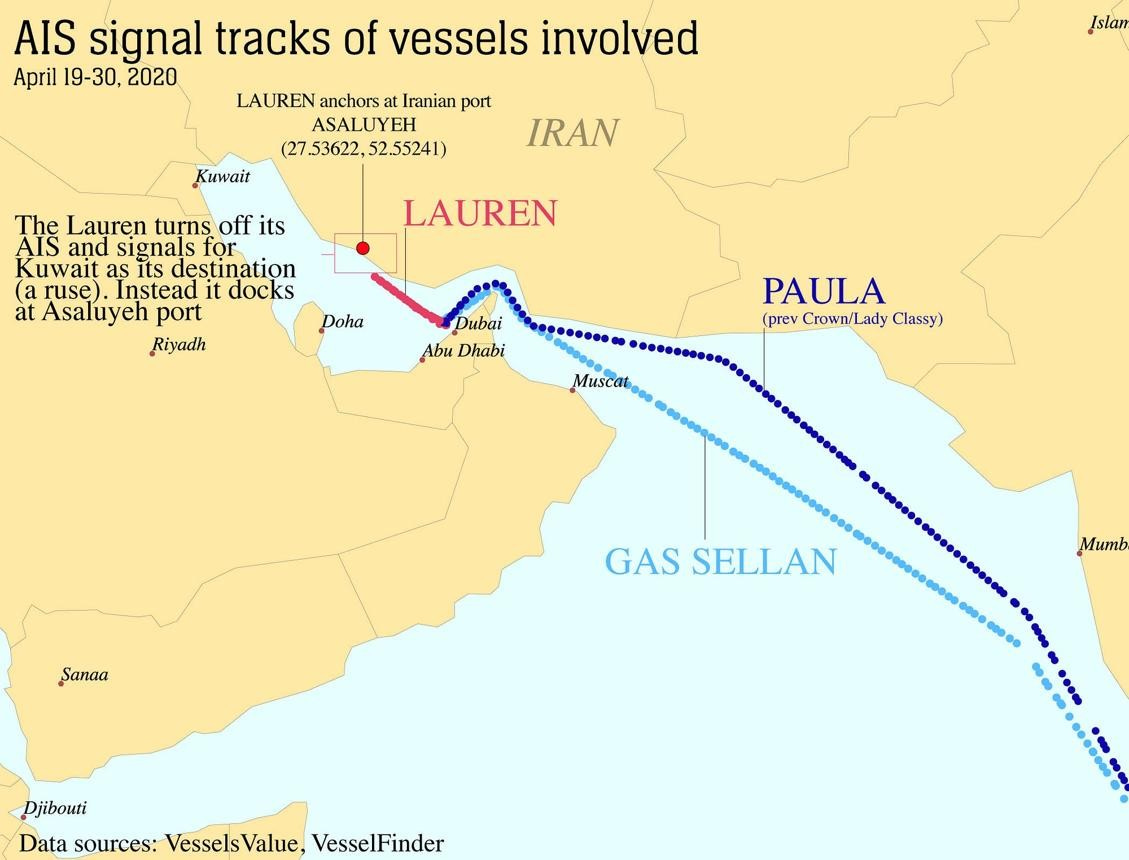
What you’re seeing, operationally:
AIS suppression and spoofing. Tankers either go “dark” or broadcast false locations, making them appear elsewhere or invisible to standard tracking.
False flags and identity switching. Vessels frequently change names and registry flags, sometimes mid-voyage, masking ownership and jurisdiction.
Shell companies and front networks. Entire logistics chains are run through layered corporate fronts in places like the UAE, Hong Kong, and Panama to disguise origin and payment flows.
Ship-to-ship transfers at sea. Oil is moved between vessels in international waters, breaking the traceable chain of custody.
Coastal “hugging” routes. Tankers stay close to Iranian or neighboring territorial waters to complicate interdiction and raise escalation risk for any enforcing navy.
Adaptive routing and deception behavior. Windward tracking shows vessels altering routes, delaying, or reversing course in response to enforcement pressure.
Bottom line: This is not random smuggling. It is a state-tolerated, systematized shadow logistics network - a maritime version of shadow banking. It is designed to operate in the gray zone: just below the threshold that would justify kinetic enforcement, but effective enough to keep oil and revenue flowing.
China: The Long Game
China watches all of this through a financial lens. Beijing does not yet have a currency that can fully replace the dollar because the yuan is not freely convertible, China maintains capital controls, and global investors still want the legal depth and liquidity of United States markets.
But China does not need to replace the dollar overnight. It only needs to create enough yuan-based settlement routes to reduce American coercive power at the margins. Reporting on Iran-China oil trade has emphasized that yuan settlement helps both countries reduce exposure to the dollar-dominated sanctions system. Al Jazeera
See The Rules to the Ancient Chinese Strategy Game: “GO”
Petrodollar: Not collapse, but leakage
That is the real risk to the petrodollar: not collapse, but leakage. Every oil cargo settled outside the dollar, every Gulf hedge toward China, every non-dollar payment rail, every sovereign wealth fund decision to diversify reserves, and every American threat to weaponize finance teaches other countries to ask a simple question: how much dollar exposure is safe?
The dollar remains powerful because there is still no full substitute:
The United States Treasury market is deep.
The United States has rule-of-law advantages.
American financial markets are liquid.
The Federal Reserve can provide crisis liquidity at a scale no other central bank can match.
Treasury data still show huge foreign holdings of United States Treasury securities, with Japan and other major financial centers holding large positions. Treasury International Capital data
But strength is not the same as invulnerability.
What does the UAE’s OPEC exit foretell about credit swaps and Treasury holdings? It suggests that Gulf financial strategy will become more transactional. If Washington offers credible dollar liquidity during crisis, Gulf sovereign wealth funds have a stronger reason to keep large dollar assets, including Treasuries.
When Washington continues to humiliate partners publicly, weaponizes tariffs carelessly, or fails to protect Gulf infrastructure, those same funds will not dump Treasuries overnight, because that would hurt their own portfolios:
But they will diversify at the margin.
They will buy more Asian assets.
They will consider more yuan settlement for China-linked trade.
They will hold more gold.
They will build more bilateral payment arrangements.
They will insist on options.
That is how reserve systems erode. Not with one press conference. Not with one BRICS summit. Not with one UAE decision.
They erode when the country at the center of the system treats trust as free.
But it also creates temptation. The more debt rises, the more Washington depends on the world continuing to believe that American politics will not destroy American credit.
This is how we have financed every war, and American power projection, since the 1970’s.
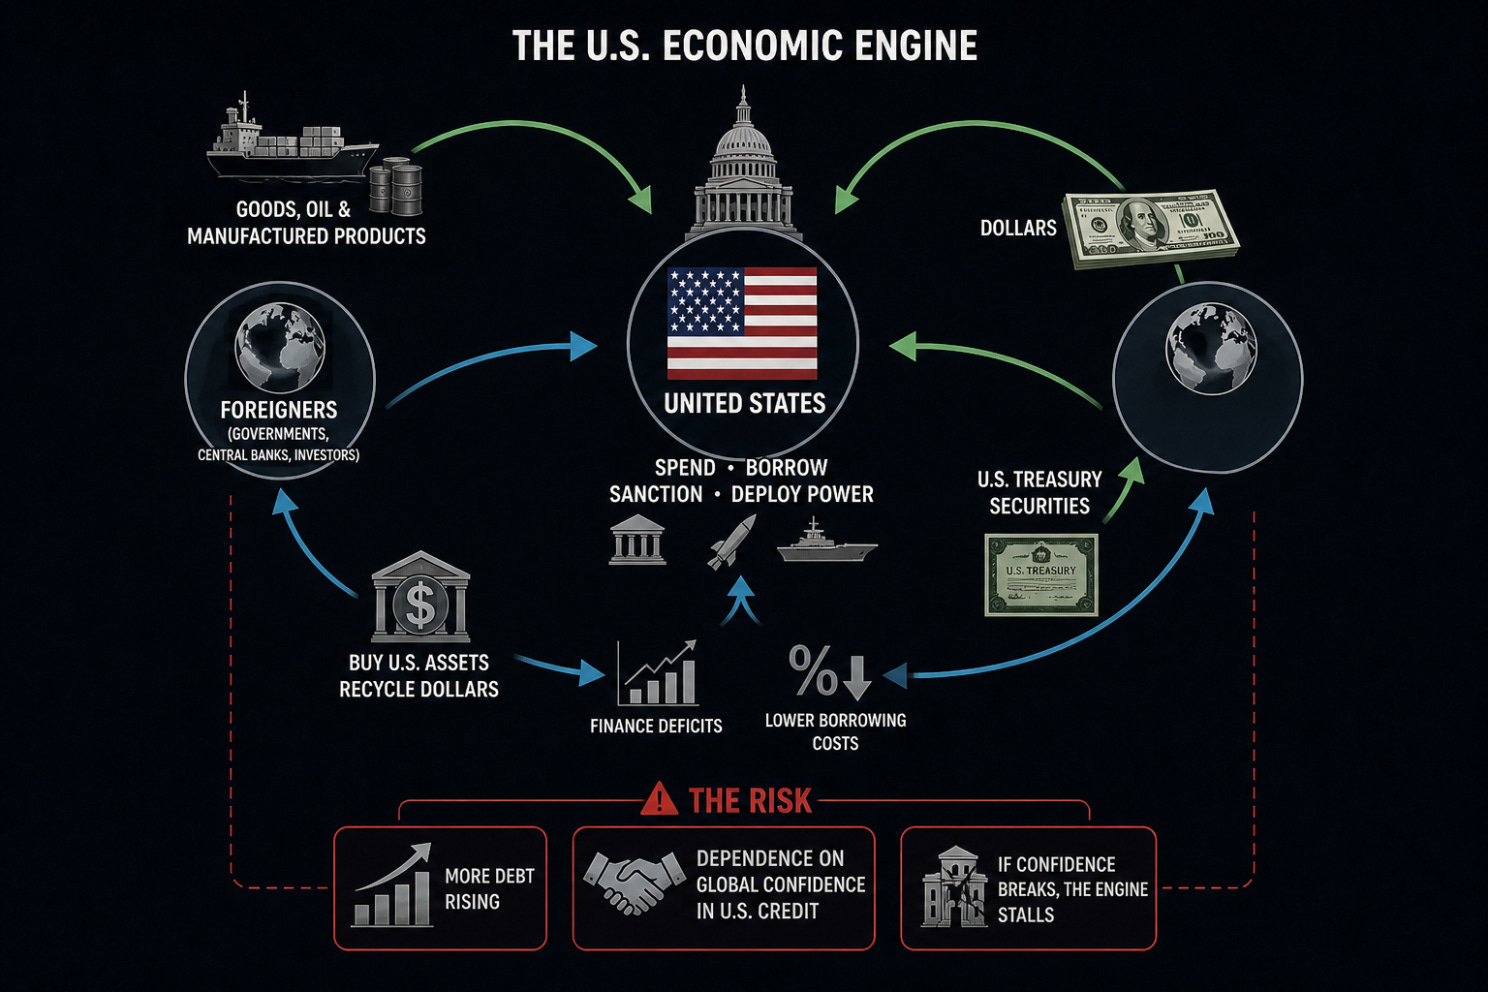
The engine that feeds the beast
For 9th grade students, the household analogy is imperfect but useful. Imagine a family with the best credit card in town. Everyone trusts them. Stores accept their card. Banks lend to them. Their neighbors even hold their IOUs because they believe the family always pays.
That family can live better than its income for a long time.
But if the family starts insulting lenders, picking fights with stores, borrowing faster every year, and arguing publicly about whether to pay its bills, the card still works - until the day the interest rate rises and everyone quietly asks for more collateral.
That is where America is now.
The petrodollar is not dead. The dollar is not about to be replaced by the yuan. BRICS is not yet a monetary NATO:
But the world is learning how to route around American pressure.
The Gulf is learning how to diversify security.
China is learning how to settle more trade in its own currency.
Iran is learning how to exploit maritime and legal seams.
The UAE is signaling that national flexibility now matters more than cartel discipline.
The sober conclusion is this: the dollar will remain the central currency of the world as long as the United States remains the most trusted provider of liquidity, security, law, market depth, and strategic steadiness.