
National Intelligence Estimate (NIE) - The Unintended Consequences of War
One month ago, on March 18, 2026, an Iranian ballistic missile struck Qatar’s Ras Laffan Industrial City, damaging critical infrastructure at the world’s largest LNG hub. The attack, retaliation for earlier strikes on Iranian gas fields, caused extensive damage.
The attack forced an emergency restructuring of global energy supply, with major impacts expected for Asian and European buyers.
Bottom line:
This was not just a strike on Qatar. It was a strike on a choke point inside the global cost-of-living system. According to Reuters, QatarEnergy chief Saad al-Kaabi said the attack damaged two of Qatar’s fourteen liquefied natural gas, or LNG, trains and one gas-to-liquids facility, taking 12.8 million metric tons per year of LNG capacity offline for three to five years.
That 17 percent figure refers to Qatar’s LNG export capacity, not 17 percent of total world supply. But because Qatar is one of the world’s largest LNG exporters and because almost all of its LNG moves through one narrow route, the strategic effect is global anyway.
What happened
Ras Laffan Industrial City is not an ordinary plant. It is the core of Qatar’s gas export machine, much like Kharg Island is to Iran. Reuters reports that Qatar’s LNG liquefaction plants and export infrastructure are concentrated almost entirely at Ras Laffan, around 80 kilometers northeast of Doha.
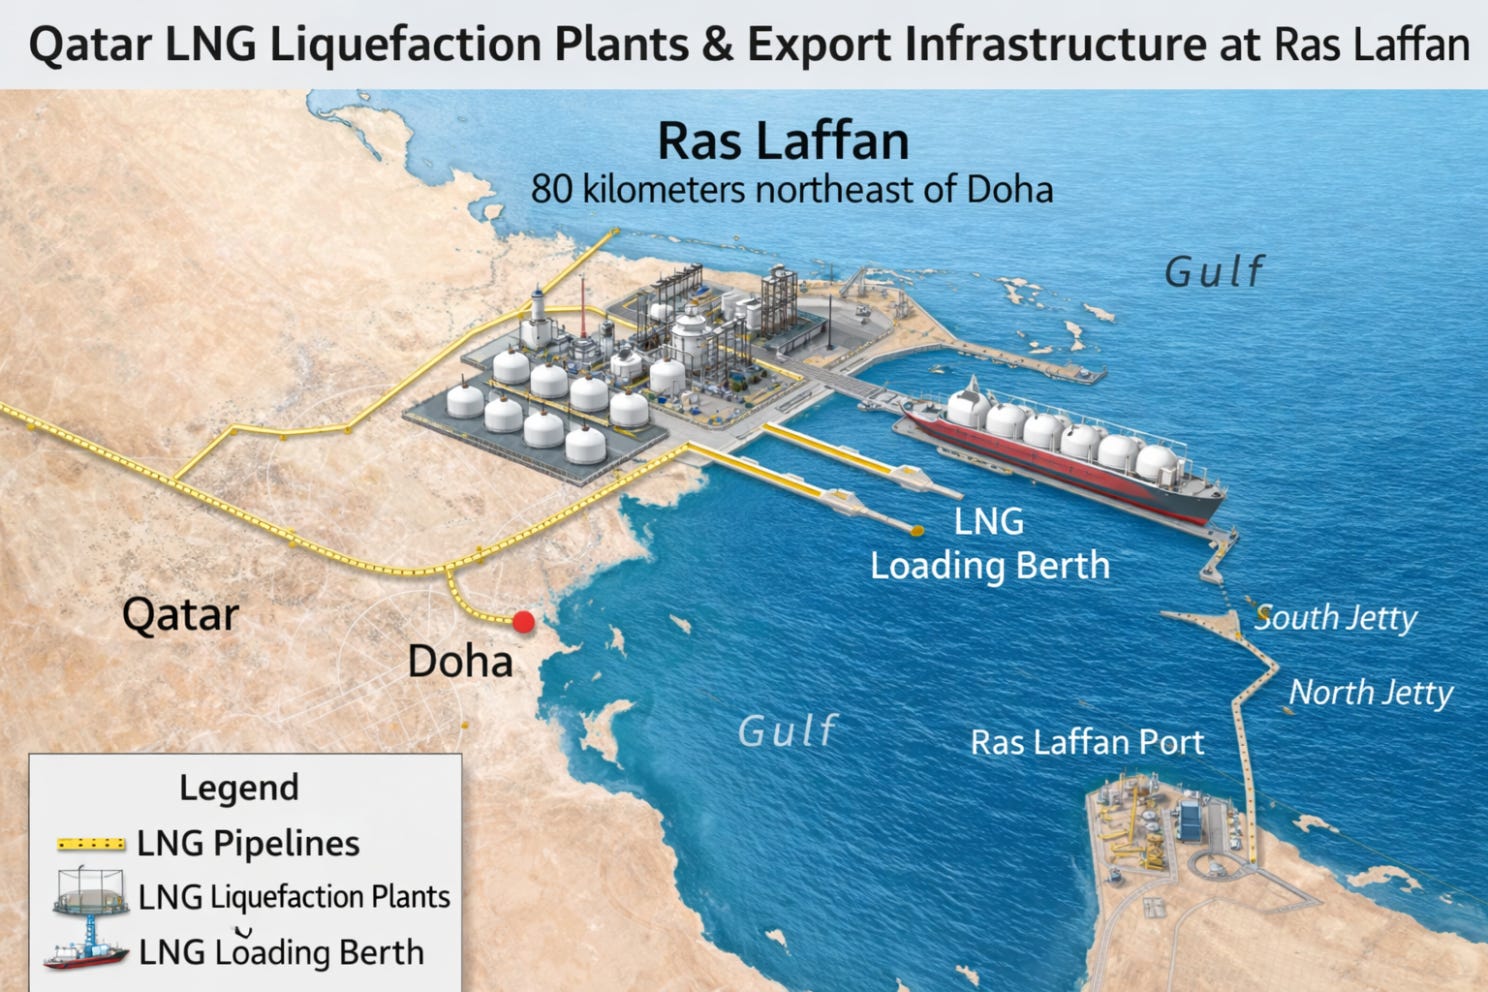
The same reporting notes that all Qatari LNG cargoes must exit the Gulf through the Strait of Hormuz. That concentration is what turned one successful strike into a systemic shock.
Damage in one place immediately became a problem for power utilities in Europe, import planners in China, fertilizer buyers, shipping insurers, and energy traders around the world.
The attack’s physical damage matters because LNG infrastructure is slow, specialized, and hard to repair. An LNG train is a complex industrial system that chills gas to extremely low temperatures so it can be loaded on ships. You do not replace those parts from a warehouse shelf. Reuters reports the damage sidelined 12.8 million metric tons per year and halted repairs until hostilities ease.
The same report says the strike also hit one gas-to-liquids unit and reduced output of condensate, liquefied petroleum gas, helium, naphtha, and sulphur. In plain English, this was not a single-pipe problem.
It was a multi-product industrial wound.
Why one strike matters so much
The world energy system has a hidden weakness: too much supply depends on too few places. The U.S. Energy Information Administration says about one-fifth of global LNG trade moved through the Strait of Hormuz in 2024, primarily from Qatar.
The International Energy Agency says about 93 percent of Qatar’s LNG exports passed through that strait in 2025, representing almost one-fifth of global LNG trade, and it adds that there are no alternative routes to bring those volumes to market.
That means there are really two layers of risk here. First, the route can be blocked. Second, even if the route reopens tomorrow, damaged production capacity at Ras Laffan still cannot magically return. Shipping access and physical output are two separate problems, and this conflict has created both.
That distinction is what many readers need to understand.
A tanker delay is painful.
A destroyed industrial train is something else.
It is the difference between traffic backing up on a bridge and a factory burning down.
Reuters reported that analysts at S&P Global, ICIS, Kpler, and Rystad cut the global LNG supply outlook by as much as 35 million tons this year after factoring in direct damage in Qatar, the Strait crisis, and delays to new supply. The same reporting said that amount is roughly equal to about 500 LNG cargoes.
That is why one strike can keep echoing for years, long after the news cameras move on.
Battle damage assessment
The cleanest battle damage assessment now available is this: two LNG trains damaged, one gas-to-liquids facility damaged, 12.8 million metric tons per year of LNG capacity out, repairs likely to take three to five years, and roughly 20 billion dollars in annual lost revenue for QatarEnergy according to its chief executive. Reuters also reported around 26 billion dollars in infrastructure damage and a likely delay to Qatar’s North Field expansion. This matters because the strike did not merely interrupt current sales.
It may also delay the next wave of future supply that the market had been counting on to ease prices later this decade.
That is the core lesson.
Modern war does not need mass bombing to create strategic effect. It needs precision against a highly connected node. Ras Laffan was such a node. It linked the shared gas reservoir under the Gulf to export terminals, long-term contracts, petrochemical feedstocks, industrial gases, and the electricity systems of importing states.
Hit the node, and the ripple moves outward through contracts, shipping schedules, spot prices, insurance rates, public budgets, and household bills.
Why Europe and China both feel this shock
China is exposed more directly than Europe. Reuters reported that China relied on Qatar for 29 percent of its LNG imports in 2025, while India relied on Qatar for about 45 percent.
Reuters further reported that China depended on the Middle East for 49.4 percent of its total energy product imports in 2025 and that its LNG and liquefied petroleum gas imports from the Middle East were down 43 percent after the conflict spread.
China can turn to more Russian gas, domestic output, and some cargo reshuffling, but that does not make the shock painless.
It simply changes how China absorbs it.
President Donald Trump’s next meeting with Chinese President Xi Jinping is currently scheduled for May 14–15, 2026, in Beijing, after being delayed from an earlier late-March date due to the Iran conflict.
The Strait of Hormuz situation and Iran conflict are now central drivers of the agenda, particularly given China’s heavy dependence on Middle Eastern energy.
Europe is exposed differently.
It imports relatively little gas directly from Qatar compared with Asia, but it is deeply exposed to price competition and storage stress. Reuters reported that European gas storage was only around 30 percent full in early March, compared with a typical 54 percent for that time of year, and that European gas prices jumped about 30 percent after Qatar halted flows.
Reuters later reported that the European gas benchmark nearly doubled at one point as Asian buyers competed harder for replacement cargoes from the United States.
Europe does not need to be Qatar’s biggest direct customer to suffer. It only needs to be shopping in the same market at the same time.
What this means for ordinary people
This is where strategic analysis must meet everyday life. When gas prices surge, the pain does not stay inside an energy terminal. It spreads into the price of electricity, home heating, industrial production, trucking, shipping, fertilizer, and food. Reuters reported that the European Commission moved to loosen state-aid rules because soaring fuel and fertilizer prices were already hitting agriculture, road transport, shipping, and energy-intensive industries.
Reuters reported that the International Monetary Fund warned Europe not to try to cushion too much of the energy shock because the fiscal cost would be high and price signals still matter.
In simple terms, governments are already being forced to choose between letting families and firms absorb the pain or asking taxpayers to absorb it instead.
The grocery-store effect is real.
Natural gas is not only a fuel. It is also a feedstock for fertilizer. Reuters reported that a United Nations agency warned fertilizer shortages tied to the Iran war were a major concern for the developing world.
Remember how grain shortages led to the Arab Spring?
Reuters then reported that global fertilizer prices had risen so sharply that U.S. buyers were redirecting imported fertilizer overseas to capture higher prices.
That is how a single missile strike in the Gulf can end up affecting harvest costs, food affordability, and political stability far from the battlefield.
In fragile countries, that can become a civil-order problem. When fuel rises, transport rises. When transport rises, food rises. When food rises in poor or heavily indebted states, the stress does not stay economic for long.
It becomes political.
That is one reason this conflict is so dangerous. The second- and third-order effects can be felt in countries that had nothing to do with the original exchange of fire.
ExxonMobil and the American angle
ExxonMobil sits on both sides of this story:
On the downside, Reuters reported that Exxon held stakes in the damaged Qatari LNG trains.
On the upside, Reuters reported that Golden Pass LNG in Texas, a joint venture owned 70 percent by QatarEnergy and 30 percent by ExxonMobil, produced its first LNG at the end of March and is designed to add 18 million metric tons per year when fully complete.
Reuters then reported that Golden Pass was still in commissioning mode and operating at only about one-third of the first train’s intake capacity, with its first export still uncertain.
The practical meaning is simple: Exxon is exposed to the damage in Qatar, but it also stands to benefit from higher prices and from a stronger long-term market for U.S. replacement supply.
That does not mean Exxon or the United States can simply snap their fingers and replace Qatar. Reuters reported that Italy’s Edison expects U.S. supply to help fill part of the gap.
But Reuters shows why this is only a partial answer: prices rise faster than replacement volumes appear, and Europe and Asia then compete harder for the same Atlantic Basin cargoes.
In the near term, the United States benefits from pricing power. In the medium term, it benefits from demand for new export capacity. In the immediate term, however, it still cannot fully erase the hole left by damaged Qatari trains.
Who benefits from the gap
The first beneficiaries are other exporters with cargoes already on the water or with flexible destination contracts:
U.S. LNG sellers benefit.
Some Australian producers benefit.
Traders with optionality benefit.
Reuters reported that shares of Western gas exporters jumped as Qatari flows dried up, while Reuters reported that benchmark Asian LNG prices rose nearly 40 percent in one day during the early phase of the shock.
Higher prices create winners, but they do not create enough molecules. That is the important difference.
Profit can move immediately. New physical supply cannot.
Russia may also gain indirectly in some markets if buyers become more desperate for any available gas, although sanctions, infrastructure limits, and politics still constrain that upside. Africa has longer-term opportunity, especially where projects can reach final investment decisions faster because the market now sees a more durable shortage.
But nobody should pretend there is a painless substitute sitting on the shelf. The same Reuters report that described the 35 million ton hit also explained why price-sensitive buyers in South and Southeast Asia would be forced to curb gas use. Some countries do not replace missing LNG.
They simply consume less energy and endure the consequences.
The Iran-Qatar complexity
Qatar is officially Muslim and predominantly Sunni. But Qatar has long had to manage a pragmatic relationship with Iran because both countries share the world’s largest natural gas field. The Associated Press explains that the field is called North Field on the Qatari side and South Pars on the Iranian side. Reuters likewise notes that Qatar shares its gas fields with Iran.
That shared geology created years of practical coexistence. War has now collided with that coexistence, and that is one reason the strategic picture is so tangled. Energy geography does not obey sectarian slogans.
That is where the law of unintended consequences comes in.
A conflict that began with one set of military and political goals has now damaged a shared energy ecosystem, shaken customers in Europe and Asia, enriched some competitors, increased the leverage of shipping insurers and traders, raised subsidy pressure on governments, and heightened the risk of public anger in import-dependent states.
None of that was the clean, linear outcome promised by anyone. It is the messy reality of a tightly connected world.
The three time horizons that matter
Short term, the main story is panic pricing, emergency cargo redirection, and storage anxiety.
Mid term, the story becomes industrial slowdown, higher public subsidies, more expensive fertilizer, and heavier competition between Europe and Asia for non-Qatari cargoes.
Long term, the story becomes structural: more money flows into U.S. LNG, more buyers diversify contract portfolios, more states rethink energy security, and more military planners treat export terminals and choke points as primary targets, not peripheral ones.
Each phase has its own cost center, and together those costs can plausibly run into the trillions of dollars over several years when one adds lost output, consumer inflation, subsidy spending, shipping disruption, insurance, delayed investment, and lower economic growth.
That is from just one missle attack.
That trillion-dollar judgment is an inference from the scale and duration of the shock documented by Reuters, and the International Energy Agency, not a single audited line item from one institution.
Final judgment
The world should read this attack for what it is: a demonstration that one precise strike against a concentrated energy hub can raise power prices, tighten fertilizer markets, distort shipping, reshape state budgets, and worsen geopolitical competition for years.
Even if the Strait of Hormuz stays open from this point forward, the destruction at Ras Laffan does not simply reverse itself.
That is why this event matters so much.
It is a warning about modern vulnerability.
One missile can do more than destroy steel. It can bend time, budgets, politics, and strategy.
And if this conflict with Iran continues to widen, then the strike on Qatar may come to look less like the peak of the danger than the opening lesson.
The lesson now confronting policymakers is stark and unforgiving.
What began as calibrated war of choice has already spilled into the arteries of the global economy, and each additional strike narrows the space for control while expanding the scope for unintended escalation.
Diplomacy is no longer a parallel track to military action - it is the last remaining mechanism capable of preventing a regional conflict from hardening into a catastrophic systemic one.
The actors involved still have agency, but that window is closing rapidly under the weight of market shocks, alliance pressures, and operational momentum.
History is unambiguous on this point: wars rarely begin because they are necessary, but because they are allowed to continue one step too far. As Otto von Bismarck is credited with observing, “Preventive war is like committing suicide for fear of death,” a reminder that the decision to act is always easier than the decision to stop.
Just a thought. Have a pleasant day.
Another great analysis, and the Bismarck quote is very prudent. I wonder if there are some hidden yet intended consequences, such as the US LNG exports.
With several major projects scheduled to come online over the coming 12 months. By the end of 2027, the U.S. is expected to increase its export capacity by approx. 20%, becoming the world's leading LNG exporter.