
Millennials and GEN Z - Wakeup Call - Before the Margin Call
By: Ken Robinson
There is a dangerous psychological transition taking place inside the American economy right now.
The public sees rising markets, record valuations, nonstop artificial intelligence hype, celebrity chief executives, and another flood of social media experts insisting that a new technological revolution has permanently changed the rules of economics.
We have heard this story before.
The language changes. The technology changes. Human behavior does not.
What we are witnessing today is not merely a strong market. It is a market increasingly dependent on belief:
Belief that artificial intelligence will justify nearly any valuation.
Belief that deficits no longer matter.
Belief that the Federal Reserve can indefinitely stabilize markets without consequence.
Belief that government debt can expand forever without triggering structural instability.
Belief that liquidity itself is now economic policy.
Belief that the old rules of risk no longer apply because the new technology is too important to fail.
That is not investing. That is faith.
And faith-driven markets eventually collide with reality.
The warning signs are no longer isolated. They are systemic. The Federal Reserve warned in its May 2026 Financial Stability Report that valuation pressures in residential real estate remain elevated, that some commercial real estate pressure remains a financial concern even as prices stabilize, and that riskier firms and households still require monitoring inside a system already conditioned to expect rescue. Federal Reserve Financial Stability Report, May 2026.
That last point matters because the most dangerous bubbles are not built only on bad math.
They are built on bad memory.
A generation of younger investors has come of age in a world where every market seizure eventually seemed to produce a rescue. After 2008, after the pandemic panic, after repeated banking scares, after every near-crisis, the lesson absorbed by millions was simple: buy the dip, wait for the cavalry, and assume the Federal Reserve or Washington will not allow too much pain.
That belief may be understandable. It is also dangerous.
The political setting has made that danger sharper. On May 22, 2026, Kevin Warsh was sworn in as the new chair of the Federal Reserve at a White House ceremony, replacing Jerome Powell after a contentious transition.
That alone does not cause a market crisis.
But it does place monetary policy, inflation control, central bank independence, interest-rate politics, and market confidence directly at the center of the current economic moment. Associated Press report on Warsh swearing-in Reuters report on the transition.
Markets can tolerate high valuations. They can tolerate political noise. They can tolerate uncertainty. What they struggle to tolerate is the sudden realization that the assumptions holding the entire structure together were too optimistic.
The Surface Looks Strong. The Substructure Looks Fragile.
There is a growing disconnect between what Americans are told about the economy and what many families are actually experiencing in everyday life:
The stock market reaches record highs.
Artificial intelligence companies dominate headlines.
Wall Street celebrates.
Politicians claim the economy is strong.
Financial television fills the day with confidence, momentum, and expert certainty.
Yet millions of Americans simultaneously struggle with rising grocery bills, expensive housing, crushing debt, stagnant wages, healthcare costs, insurance increases, and the growing feeling that the system no longer works for ordinary people.
Both realities can exist at the same time.
That is what makes this moment dangerous.
Financial markets are not the same thing as the lived economy.
A rising index can conceal pressure inside households.
A handful of dominant technology stocks can lift the market while large parts of the country feel stuck, indebted, priced out, and increasingly distrustful of every institution telling them everything is fine.
The pressure points are not difficult to identify:
The national debt continues rising.
Interest payments are consuming a larger share of federal resources.
Housing affordability remains broken for much of the middle class.
Credit stress continues to show up in household balance sheets.
Commercial real estate remains a slow-moving problem for regional banks and lenders.
Artificial intelligence investment may support near-term growth, but households and non-AI businesses still face major headwinds from tariffs, labor constraints, uncertainty, and affordability pressures. Deloitte US Economic Forecast, March 2026.
This is how financial stress often appears before it becomes obvious. It does not announce itself as a single thunderclap. It appears as a pattern: elevated valuations, narrowed market leadership, debt accumulation, political pressure on monetary policy, consumer strain, geopolitical volatility, and a public increasingly trained to believe that rescue is automatic.
That is the setup. Not certainty of collapse. Not a prediction that markets must crash tomorrow.
But the kind of environment where complacency becomes expensive.
The Crash Pattern: Different Decades, Same Human Error
To understand the risks ahead, young Americans first need to understand how financial bubbles work.
A financial bubble occurs when excitement, speculation, and emotional herd behavior push prices far beyond what something is realistically worth. People stop asking whether an investment makes sense and instead begin believing prices can only continue rising forever.
That is why this moment feels so familiar. The historical parallel is not that today is identical to 1929, 2000, or 2008. History rarely repeats in exact costume. The parallel is psychological.
Each major crash was preceded by a story that sounded intelligent at the time.
The 1929 Stock Market Crash
The 1929 Crash Felt Around the World - Led to the Rise of Fascism - Sound Familiar
In the 1920s, millions of Americans believed the stock market could only go up. It was the age of new technology, new consumer credit, new radios, new automobiles, new confidence, and a public convinced that prosperity had become permanent.
Many people borrowed money to buy stocks. This was called buying on margin. Investors used loans to purchase stocks they could not actually afford, hoping prices would continue rising.
When markets suddenly turned downward in 1929, panic spread rapidly:
Investors rushed to sell.
Banks failed.
Businesses collapsed.
Unemployment exploded.
The result became known as the Great Depression. Millions of ordinary Americans lost jobs, homes, savings, and farms.
The lesson was simple: debt and speculation become extremely dangerous when people believe risk no longer exists.
The Dot-Com Bubble of 2000
The Madness of the Dot.com Boom & Crash
In the late 1990s, investors became convinced the internet would permanently change civilization.
That part was true. The internet did change the world.
But investors made a critical mistake: they confused transformational technology with rational pricing.
Companies with little revenue and sometimes no profits saw their stock prices skyrocket simply because they had .com attached to their name:
People stopped evaluating businesses realistically.
Emotion replaced discipline.
The story became more important than the balance sheet.
We are seeing this with the AI craze.
When the bubble burst in 2000, trillions of dollars disappeared from the market. Many ordinary investors lost retirement savings and college funds.
Question: Where do you think those TRILLIONS of DOLLARS landed? Who’s wallet?
Not yours, the system was not built for you.
Again, the lesson was not that technology was fake. The lesson was that hype eventually collides with financial reality.
That is the artificial intelligence warning today. AI may genuinely transform civilization. But that does not automatically justify every valuation attached to it. The internet was real. The bubble was also real.
Both things were true at the same time.
The 2008 Mortgage Collapse
2008 Crash: Predictable
The 2008 financial crisis followed a similar pattern.
The simplified narrative that “banks alone caused everything” is historically incomplete.
But the opposite claim — that “government alone caused everything” — is also incomplete.
The reality is that government incentives and Wall Street profit incentives fused together into a mutually reinforcing system where everybody benefited temporarily while systemic risk accumulated invisibly underneath.
That is why the collapse became so catastrophic.
The system rewarded short-term gains while dispersing long-term risk across the entire global financial architecture:
Banks issued enormous numbers of risky home loans called subprime mortgages.
These were loans given to people who often could not realistically afford them.
Those risky mortgages were then bundled together and sold throughout the global financial system as supposedly safe investments.
Wall Street made massive profits. Ratings agencies failed to sound proper warnings. Government regulators missed growing danger signs. Politicians preferred the illusion of broad home ownership to the harder discipline of asking whether the credit structure beneath it was sound.
When homeowners began defaulting on loans, the entire system started collapsing. Banks failed. Markets crashed. Millions lost homes and jobs. Many large financial institutions received government bailouts while ordinary Americans absorbed much of the damage.
That event permanently damaged public trust because it revealed something ugly: the system could socialize losses after privatizing gains.
The current risk is not another identical mortgage collapse. The current risk is broader: a market, a government, and a public all conditioned to believe that leverage, rescue, liquidity, and confidence can substitute for discipline indefinitely.
Why This Matters Today
Today, many warning signs are appearing again, but they are scattered across the system rather than concentrated in one obvious place.
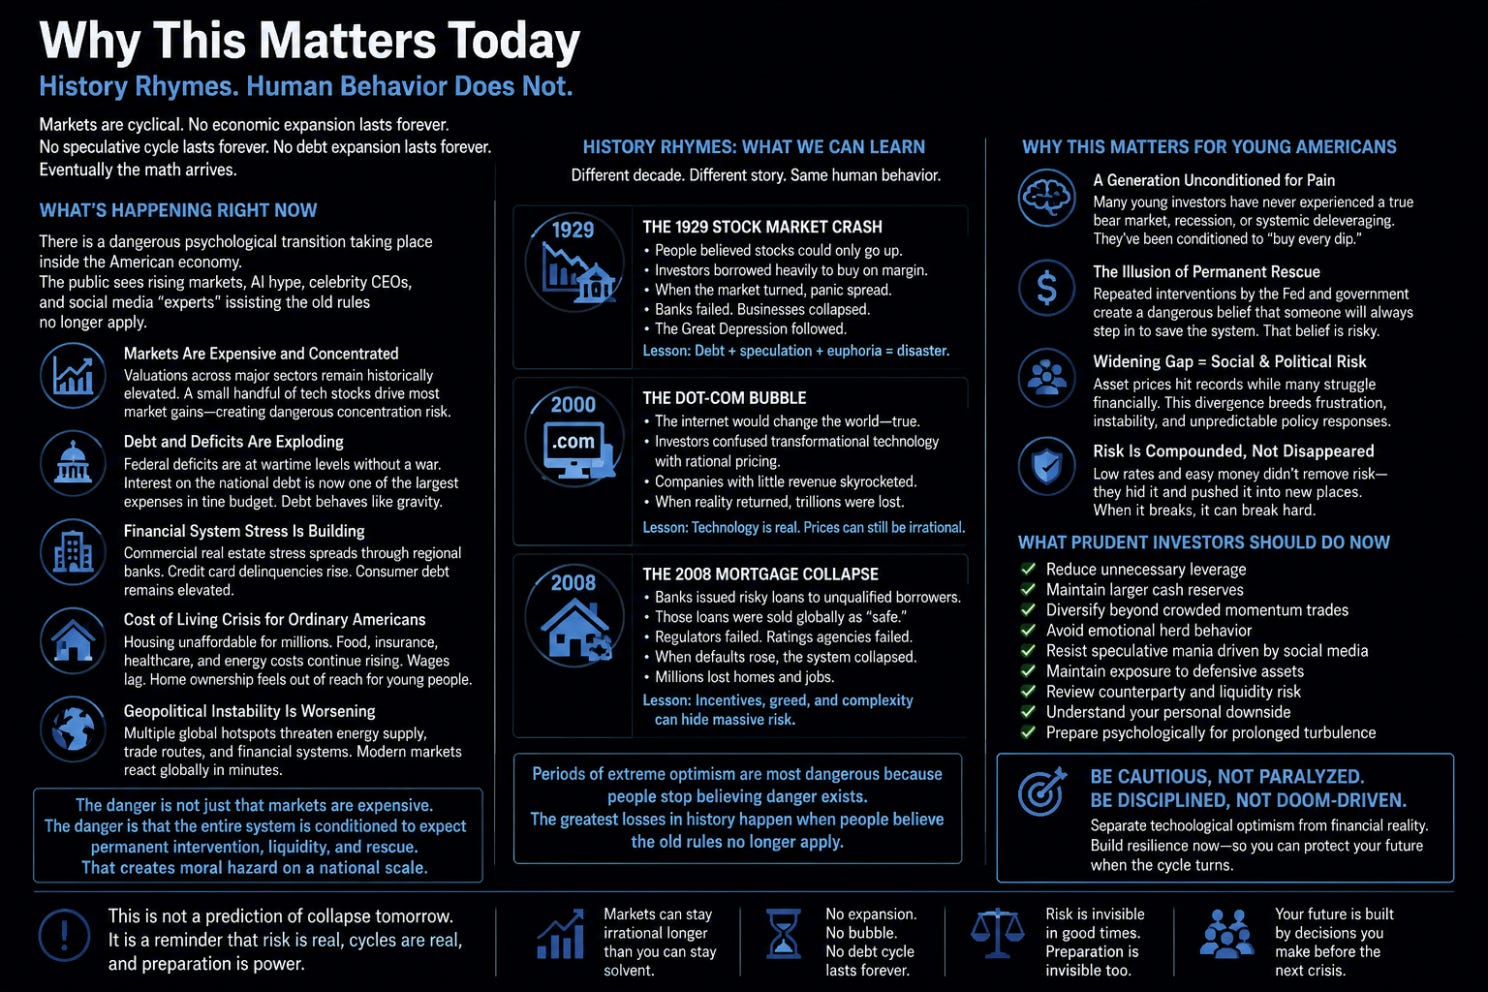
Past is Prologue
AI FOMO: New - Now - Next
Artificial intelligence - Fear of Missing Out (FOMO) has become the newest center of financial excitement. AI refers to computer systems designed to perform tasks that normally require human intelligence, such as writing, analysis, image creation, coding, and decision-making. It may transform business, medicine, education, logistics, military operations, finance, and industrial productivity over the next several decades.
That is not the problem.
The problem begins when technological possibility becomes financial religion.
Stanford economists, looking ahead to 2026, specifically identified Federal Reserve rate decisions, a weakening labor market, AI-related valuations, affordability challenges, and limited fiscal space as major issues to watch. Stanford Institute for Economic Policy Research 2026 outlook
That is the correct frame.
The problem is not one data point. The problem is the convergence of multiple pressures at once
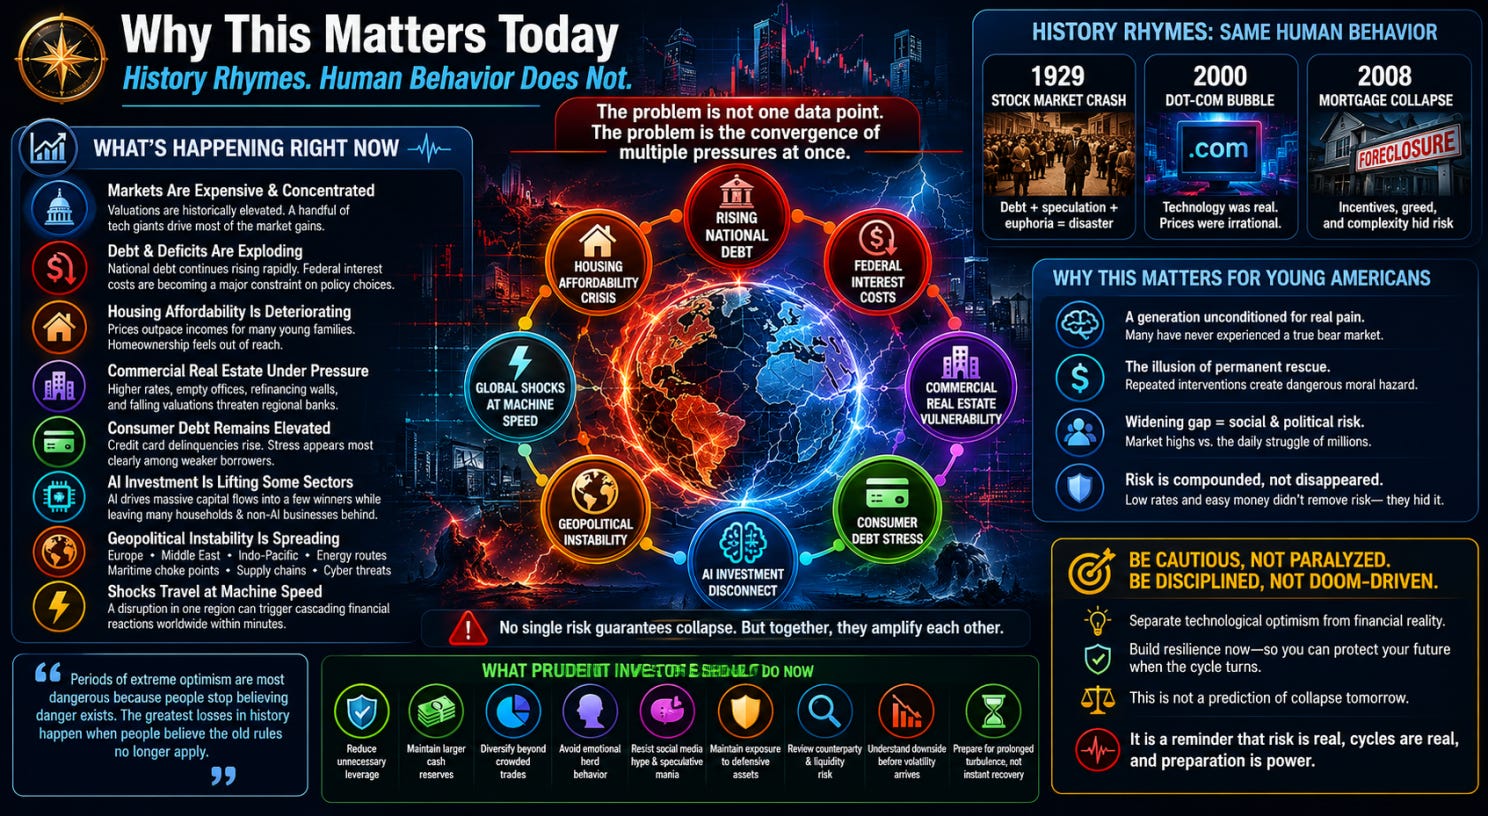
What This Means for You
National debt continues rising rapidly.
Federal interest costs are becoming a major constraint on future policy choices.
Housing affordability continues deteriorating for many young families.
Commercial real estate remains vulnerable in a higher-rate world.
Consumer debt remains elevated, with stress appearing most clearly among weaker borrowers.
AI investment is lifting some sectors while leaving many households and non-AI businesses under pressure.
Geopolitical instability is spreading across Europe, the Middle East, and the Indo-Pacific.
Energy routes, maritime choke points, supply chains, and cyber systems now transmit shocks at machine speed.
That is why the analogy to previous crashes matters. In each case, the market had a story that made risk feel outdated. In 1929, the story was permanent prosperity. In 2000, the story was the internet. In 2008, the story was sophisticated financial engineering and ever-rising home prices. Today, the story is artificial intelligence, permanent liquidity, and institutional rescue.
You should not reject technology. You need to reject magical thinking.
The Federal Reserve, Liquidity, and the Illusion of Control
Many Americans hear terms like liquidity, inflation, and Federal Reserve without fully understanding them. These terms matter.
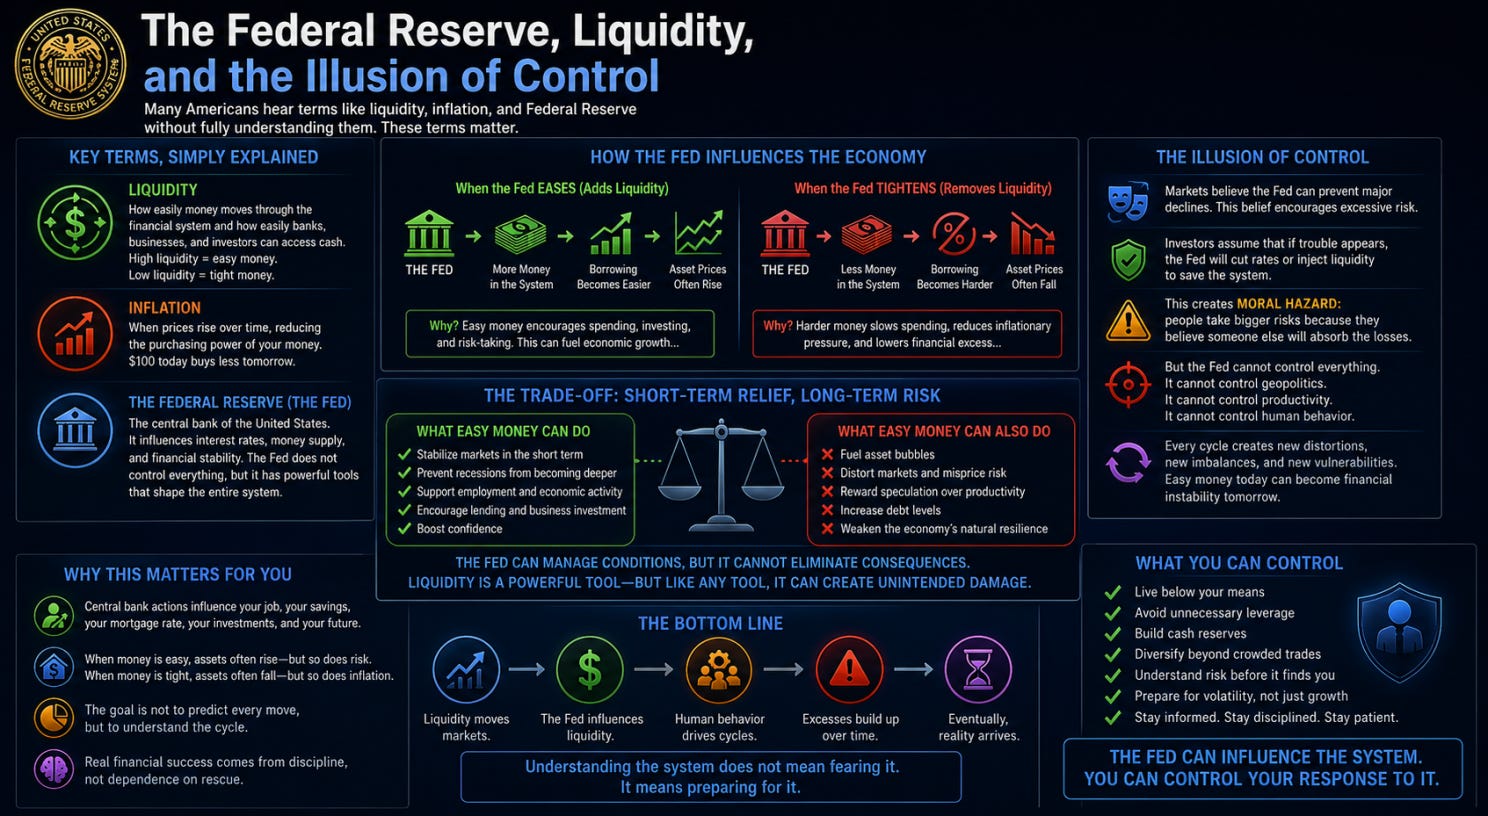
How The Ponzi Works
Inflation simply means prices rise over time, reducing the purchasing power of money. Liquidity refers to how easily money moves through the financial system and how easily banks, businesses, and investors can access cash.
The Federal Reserve is the central bank of the United States. It influences interest rates, money supply, and financial stability. Its traditional political firewall of independence is now a major question for the market.
When the Federal Reserve lowers interest rates or injects money into the system, markets often rise because borrowing becomes easier and investors take more risks. But easy money can also create bubbles. That is one of the central dangers facing the economy today.
The danger is not merely that the Fed may make a wrong decision. The danger is that too many investors believe the Fed can always make the pain go away.
That belief creates moral hazard on a national scale.
If people believe rescue is guaranteed, they take greater risks. If markets believe liquidity will always arrive, valuations stretch. If politicians believe debt can expand forever, fiscal discipline disappears. If households believe asset prices always recover quickly, they stop preparing for prolonged turbulence.
That is how an emergency tool slowly becomes a dependency.
Debt Eventually Behaves Like Gravity
Debt is tolerable until it is not. At first it feels manageable. Then suddenly it dominates everything.
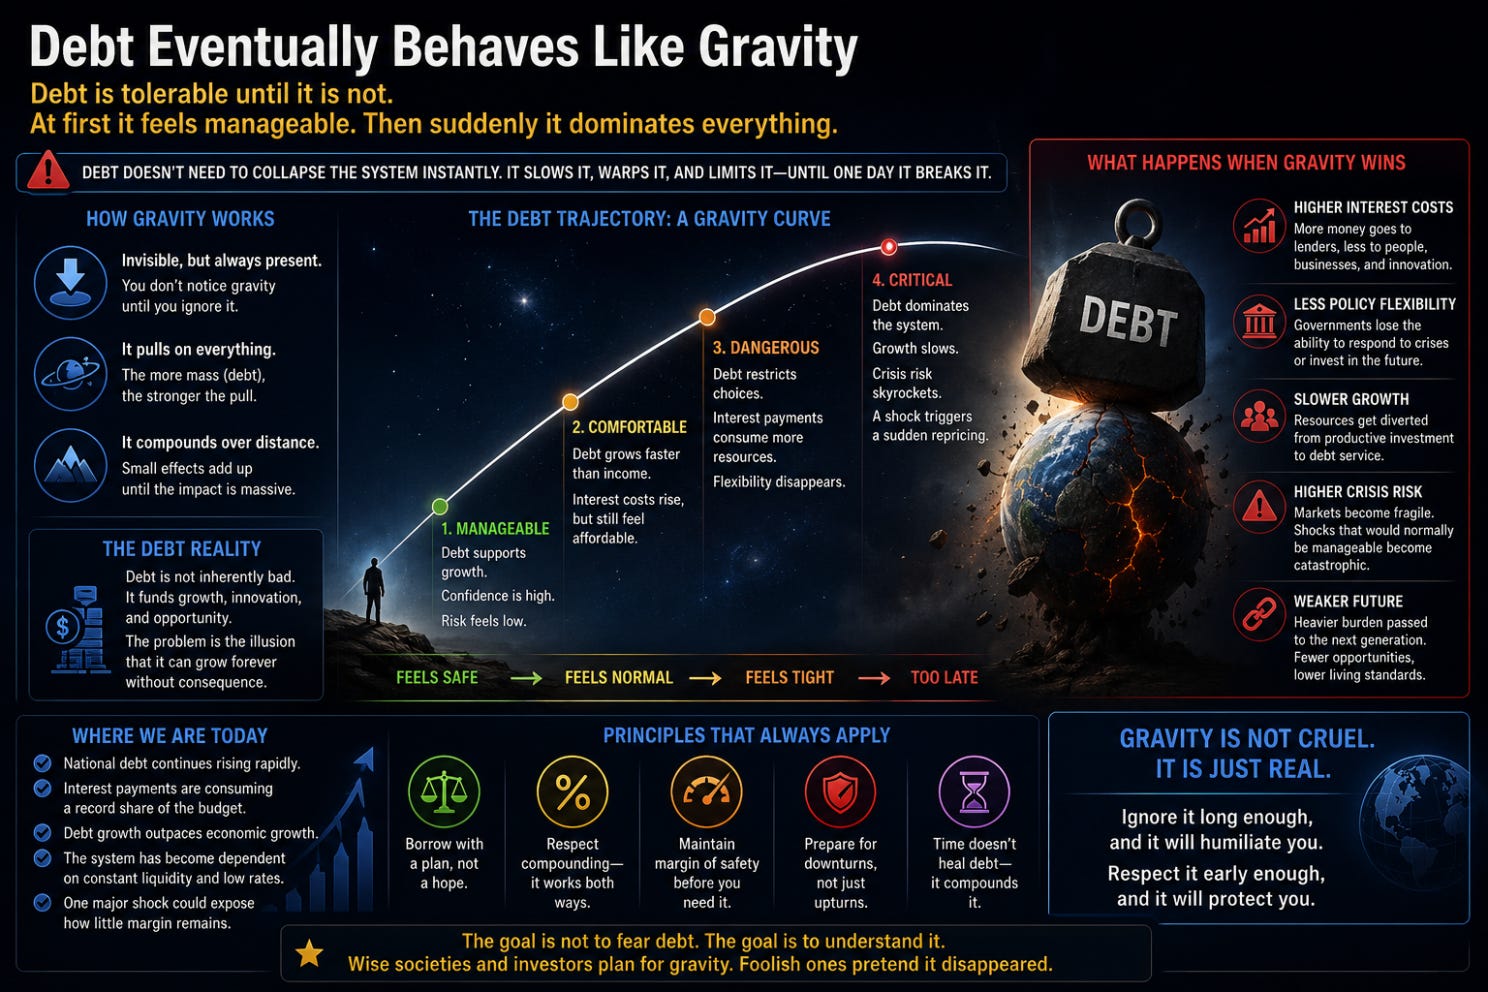
What Goes Up Must Come Down - The Question is Timing and Risk
That is true for households. It is true for corporations. It is true for governments.
Federal deficits continue expanding at levels historically associated with severe crisis or wartime spending. Interest payments on the national debt increasingly compete with defense, healthcare, infrastructure, education, and every other national priority.
That does not mean the United States is about to collapse. It does mean the country has less room for error.
Fiscal space matters because crisis response depends on credibility. A nation with strong public finances can respond to recession, war, banking stress, or pandemic shock with more flexibility.
We, as a nation, are carrying massive structural debt, the FED has fewer clean options.
The market knows this.
Bond investors know this.
Foreign governments know this.
Rating agencies know this.
Ordinary citizens may not follow Treasury auctions, but they feel the consequences through mortgage rates, credit costs, inflation, taxes, and reduced purchasing power.
The danger is not only economic. It is political. When citizens watch asset owners get richer while wages, housing, insurance, food, and medical costs squeeze working families, resentment builds.
That resentment becomes distrust. Distrust becomes political instability. Political instability eventually becomes market instability.
A foreshadowing potential for the midterms - if voters seek radical change.
The Deeper Problem Is Psychological
Free Your Mind and Your Ass Will Follow
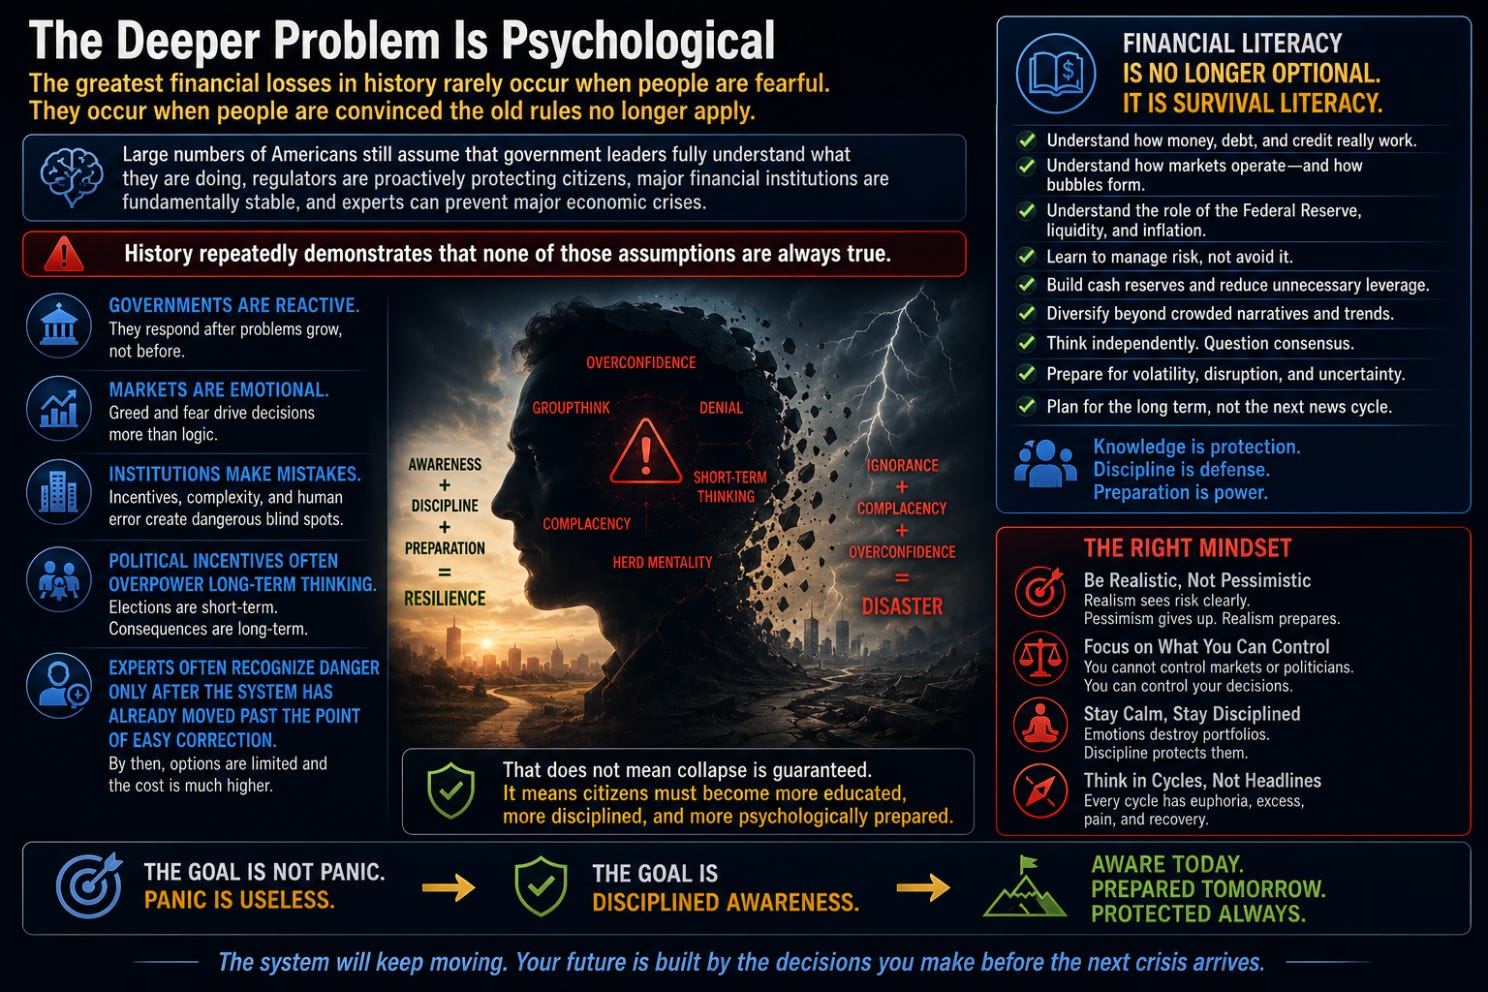
Large numbers of Americans still assume that government leaders fully understand what they are doing, regulators are proactively protecting citizens, major financial institutions are fundamentally stable, and experts can prevent major economic crises.
Not really.
History repeatedly demonstrates that none of those assumptions are always true:
Governments are reactive.
Markets are emotional.
Institutions make mistakes.
Political incentives often overpower long-term thinking.
Experts often recognize danger only after the system has already moved past the point of easy correction.
That does not mean collapse is guaranteed. It means citizens must become more educated, more disciplined, and more psychologically prepared.
Financial literacy is no longer optional. It is survival literacy.
The goal is not panic. Panic is useless. The goal is disciplined awareness.
Universal Precautions for Ordinary People
Be Prepared - Forewarned is Forearmed
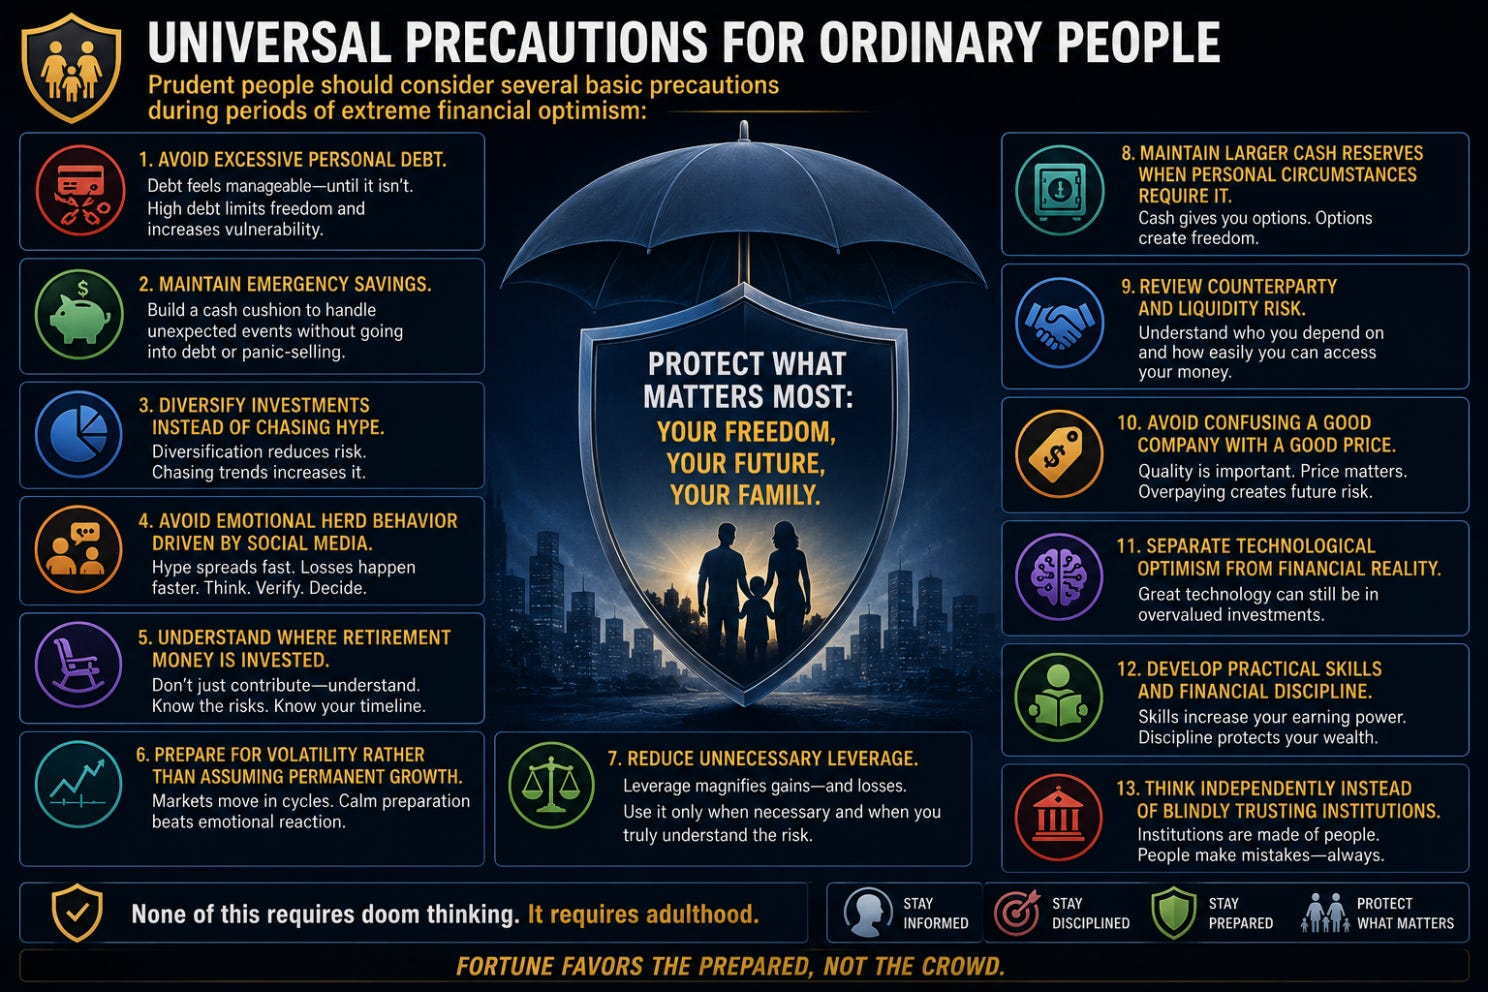
Prudent people should consider several basic precautions during periods of extreme financial optimism:
Avoid excessive personal debt.
Maintain emergency savings.
Diversify investments instead of chasing hype.
Avoid emotional herd behavior driven by social media.
Understand where retirement money is invested.
Prepare for volatility rather than assuming permanent growth.
Reduce unnecessary leverage.
Maintain larger cash reserves when personal circumstances require it.
Review counterparty and liquidity risk.
Avoid confusing a good company with a good price.
Separate technological optimism from financial reality.
Develop practical skills and financial discipline.
Think independently instead of blindly trusting institutions.
None of this requires doom thinking. It requires adulthood, because:
Economic systems are not driven primarily by morality.
They are driven by incentives.
Political systems respond to pressure.
Corporations pursue profit.
Financial markets reward momentum until reality intervenes.
Understanding that reality is not cynicism. It is maturity.
The Bottom Line
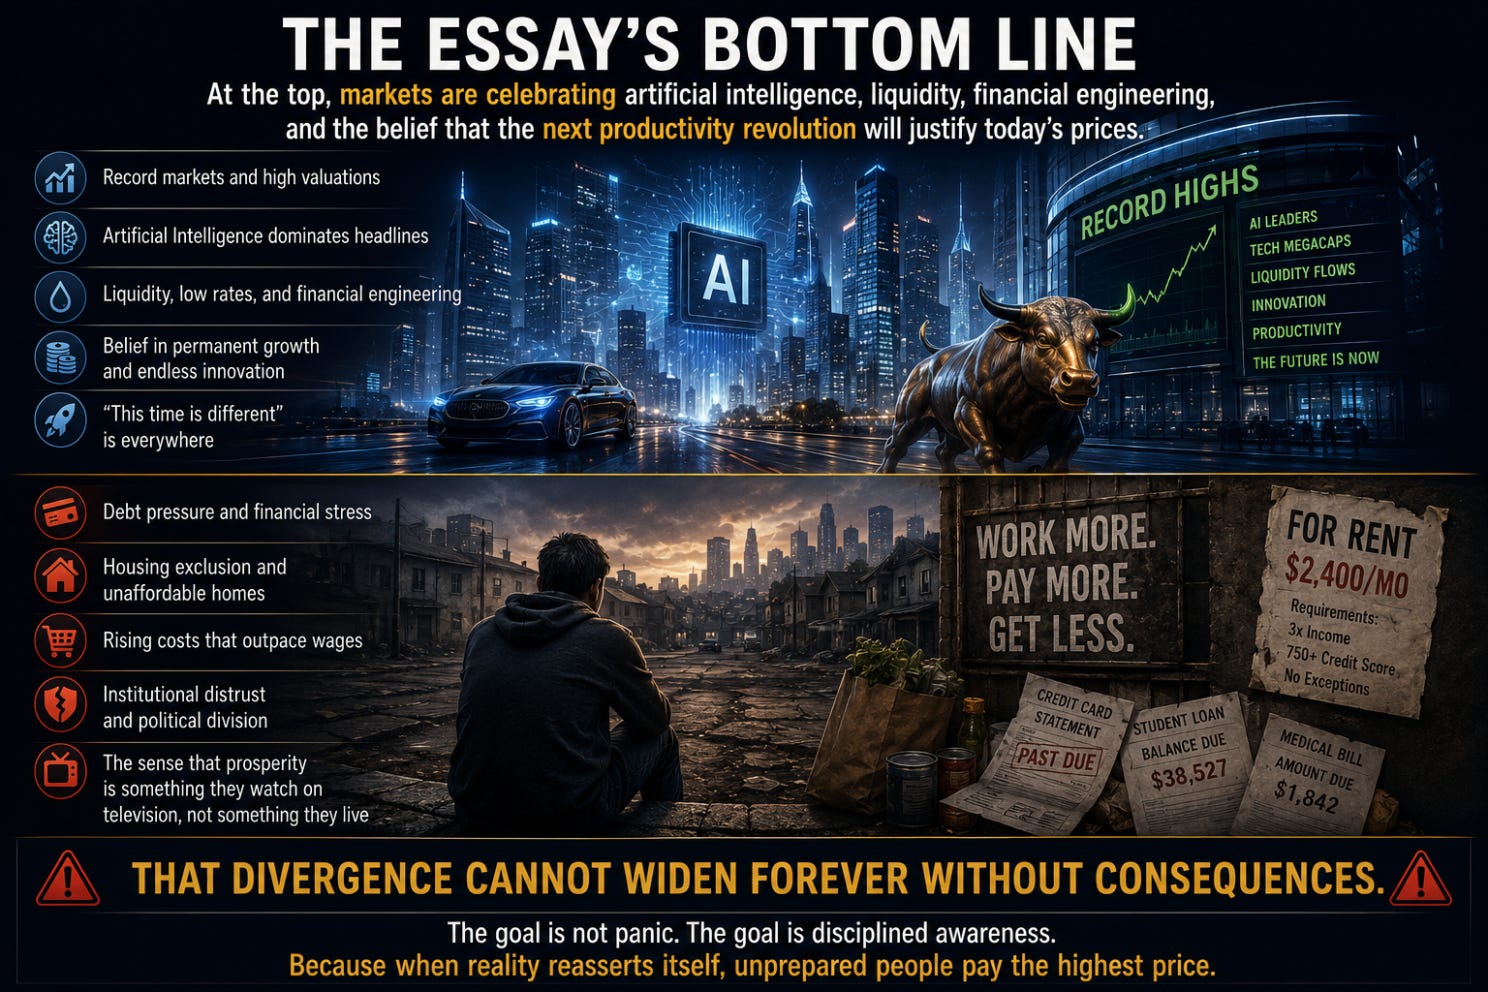
The American economy is not one thing. It is two realities moving at once.
Be Prepared - Get Educated - If it Sounds Too Good to be True: Its Likely Not True
At the top, markets are celebrating artificial intelligence, liquidity, financial engineering, and the belief that the next productivity revolution will justify today’s prices.
At the bottom, many citizens are living with debt pressure, housing exclusion, rising costs, institutional distrust, and the sense that prosperity has become something they watch on television rather than experience in their own lives.
That divergence cannot widen forever without consequences.
The comparison to 1929, 2000, and 2008 is not a prediction that the same crash will happen again in the same way. It is a warning that financial history is full of smart people explaining why this time is different right before discovering that human psychology was the constant they forgot to price.
Every major financial collapse in modern history was preceded by confidence.
That confidence became complacency. Complacency became vulnerability. Vulnerability became crisis.
The core lesson for young Americans is simple: free your mind. Question assumptions. Learn how systems actually work. Prepare before crisis arrives.
Because in difficult times, the people who survive best are rarely the people who blindly trusted the system.
Wow! Great article! You missed your calling. You should have been a financial analyst. I hope you won’t turn out to be a Cassandra. People should listen to you.
Have a pleasant day..