Iran, Hormuz, Putin, blockchain settlement, and the new investor risk map
By: Ken Robinson
The real question is not whether the latest fighting in the Persian Gulf pushed oil prices higher. It did. The deeper question is whether the United States, Europe, and investors understand that the oil market is now becoming a battlefield where missiles, sanctions, shipping chokepoints, cryptocurrency, and political psychology are converging.
The immediate facts are serious. Reuters reported that renewed United States-Iran fighting around the Strait of Hormuz sent oil prices higher before gains were partly reversed, with Brent crude futures above $101 a barrel even as prices remained down more than 6 percent for the week.
The same reporting said President Donald Trump continued to describe the ceasefire as holding despite flare-ups around a waterway that, before the war, handled roughly one-fifth of global oil supply. CBS News reported that United States Central Command said American forces conducted self-defense strikes after United States Navy destroyers were attacked by Iranian missiles, drones, and small boats in the Strait of Hormuz.
Cease Fire That Never Was
That is the narrow news.
The wider strategic meaning is more important. Iran does not have to defeat the United States Navy to change global behavior. It only has to make insurers, shippers, energy traders, and political leaders believe that a routine transit through the Strait of Hormuz is no longer routine:
That is how a weaker power uses geography against a stronger power.
The Strait of Hormuz is not just a channel of water.
It is a pressure point in the global economy.
Trump’s response, as publicly reported, has been a combination of military retaliation, blockade enforcement, negotiation, and public confidence that a deal may still be possible.
“Credibility is lost when red lines are drawn and ignored.”
Reuters reported that the United States and Iran remain no closer to ending the war, even as Washington awaits Tehran’s response to a proposal to end hostilities and move toward peace talks.
The Guardian reported that Secretary of State Marco Rubio said the United States was awaiting Iran’s response to a ceasefire proposal, while Trump suggested there would be a strong response if diplomacy failed.
That mixture is not unusual in crisis management. Presidents often signal strength and diplomacy at the same time. The risk is that adversaries, allies, markets, and domestic audiences may each hear a different message. Iran may hear hesitation. Gulf partners may hear uncertainty. Russia may hear opportunity. Investors may hear volatility.
The oil market is reacting to both physical disruption and political ambiguity.
Reuters reported last week that Brent briefly reached more than $126 a barrel amid fears of prolonged Middle East supply disruption before falling back. Crude supply losses from halted marine traffic through the Strait of Hormuz have drawn down global oil and fuel inventories as refineries try to offset shortfalls. Citi analysts, cited by Reuters, warned that oil prices could rise further if United States-Iran talks remain difficult, even though emergency inventories, weaker demand, and possible diplomatic de-escalation could limit the surge.
Volatility of Oil Pricing
PUTIN ADVANTAGE
This is where Vladimir Putin enters the picture. Higher oil prices do not simply enrich Russia in a mechanical way, because sanctions, Ukrainian strikes, infrastructure damage, and export constraints still matter. But higher prices do give Moscow more room to breathe. Reuters reported that Russia’s oil and gas tax revenues were expected to rise in May because of higher prices bolstered by the Iran war, even though revenues remain lower year-to-date. Reuters also reported that the Russian oil price used for tax calculations rose to $94.87 a barrel in April, the highest level since September 2014 and far above the price assumed in Russia’s budget.
The Kremlin’s strategic logic is simple. Every dollar added to the price of exportable Russian crude can help finance the war in Ukraine, stabilize the budget, or reduce the political pain of sanctions. But the benefit is not clean. Reuters separately reported that high oil prices would not rescue Russian growth, citing a Russian think tank that downgraded growth expectations because sanctions, Ukrainian drone attacks, and damage to oil production and exports continue to hurt the economy.
That means Putin benefits from Middle East chaos, but he does not fully control the benefit. He can exploit the price environment. He cannot make Russia’s refineries, ports, tankers, insurers, and buyers immune from pressure. Ukraine’s attacks on Russian oil infrastructure and the West’s campaign against the Russian shadow fleet continue to impose costs. The contest is no longer only about the market price of oil. It is about whether Russia can physically move, insure, sell, and settle payment for its oil under pressure.
The blockchain piece matters because it is part of Russia’s sanctions-evasion ecosystem. Reuters reported in 2025 that Russia was increasingly using cryptocurrencies, including Bitcoin, Ether, and Tether, in oil trade with China and India to convert Chinese yuan and Indian rupees into Russian rubles. That does not mean cryptocurrency has replaced the dollar-based energy system.
It means Russia is building alternative payment channels where sanctions, banks, correspondent accounts, and compliance screens are harder to apply.
This is the key distinction Americans need to understand. A token marketed on social media as a Russian oil-backed digital asset is not the same thing as a sovereign Russian oil instrument. The images circulating online that appear to show BBC News and Reuters stories about a Russian Oil Asset Fund, or ROAF, should be treated with extreme caution. I found no verified BBC or Reuters report confirming that Putin launched an official oil-backed token called ROAF. The public ROAF website itself says ROAF is a speculative digital asset on Solana and is not backed by physical oil reserves or any government entity. A crypto exchange risk explainer similarly warns that ROAF should not be treated as a regulated oil fund or as a claim on physical crude oil.
That matters because the scam and the strategy can coexist. The specific ROAF promotion may be a speculative token narrative riding on fake or misleading news imagery. But the larger Russian use of cryptocurrency in oil settlement is real enough to concern policymakers.
One is a retail-investor trap. The other is a sanctions and financial-intelligence problem.
For investors, the first rule is not to confuse geopolitical storytelling with asset backing.
A token can borrow the language of oil, Russia, reserves, or sovereign finance without giving the buyer any legal claim on a barrel of crude, a pipeline, a refinery, or a government revenue stream. If the issuer is anonymous, the reserve claim is unverifiable, the legal structure is unclear, and the marketing depends on fake-looking Reuters or BBC screenshots, the default assumption should be extreme risk.
For the United States and its allies, the problem is broader. Western sanctions still rely heavily on visibility: ships, banks, insurers, registries, payment rails, and corporate intermediaries.
Russia’s counter-strategy is to reduce visibility.
The shadow fleet reduces maritime visibility. Middlemen reduce commercial visibility. Cryptocurrency and stablecoins can reduce payment visibility. False media screenshots and influencer campaigns reduce information visibility. Together, these tools create a fog around oil flows, money flows, and political intent.
The West should care for five reasons.
First, energy prices are now an inflation weapon. A prolonged Hormuz crisis can raise fuel, shipping, fertilizer, aviation, and consumer prices. That gives adversaries leverage over Western voters without firing a shot at Western territory.
Second, Russian oil revenue remains a war-financing issue. When Middle East disruption lifts global prices, Moscow may receive fiscal relief even while Ukraine is fighting to destroy Russian energy infrastructure.
Third, cryptocurrency payment channels complicate sanctions enforcement. If oil settlement increasingly moves through stablecoins, offshore brokers, informal intermediaries, and non-Western exchanges, financial intelligence services must adapt faster than regulators normally move.
Fourth, fake financial news is becoming an operational tool. A forged Reuters-style or BBC-style screenshot can move inexperienced investors into a token, launder a political narrative, or create the impression that a state-backed instrument exists when it does not.
Fifth, the United States faces an escalation-management problem. If Washington hits Iran too hard, oil may spike and Russia may benefit. If Washington looks passive, Iran may test the ceasefire and Gulf partners may hedge toward China, Russia, Pakistan, or other security alternatives. If Washington signals both confidence and threat at the same time, markets may price uncertainty rather than policy.
There are several plausible futures, and none should be treated as certain.
I. In the first scenario, diplomacy holds. Iran accepts a framework that partially reopens the Strait of Hormuz, the United States reduces pressure on Iranian vessels, oil prices ease, and Russia loses part of the windfall created by Middle East disruption. This is the best near-term market outcome, but it may leave unresolved questions about Iran’s nuclear program, Gulf security, and future maritime coercion.
II. In the second scenario, the ceasefire frays but does not collapse. Iran allows some traffic while harassing selected vessels, the United States conducts limited strikes, and oil prices remain volatile. This is the most dangerous gray-zone scenario for investors because markets may whipsaw between optimism and panic.
III. In the third scenario, the conflict widens. Iran or aligned forces strike Gulf infrastructure, the United States escalates, Israel expands operations, and insurers treat the Strait of Hormuz as a war-risk corridor. Oil prices could spike again. Russia would gain revenue per barrel, but the global shock could also weaken demand and intensify Western pressure on Russian exports.
IV. In the fourth scenario, Russia accelerates alternative oil settlement systems. Moscow uses the crisis to push buyers toward non-dollar payments, crypto-assisted settlement, barter structures, shadow insurance, and opaque intermediaries. This would not dethrone the dollar overnight. But it would continue the slow erosion of Western financial visibility.
V. In the fifth scenario, retail investors are flooded with geopolitical tokens. Scam operators and speculative promoters attach tokens to oil, war, Russia, Iran, artificial intelligence, or national security narratives. Some will use fake news graphics. Some will imply state backing. Some will collapse after insiders exit. In this environment, information hygiene becomes investor protection.
The policy answer is not panic. It is disciplined adaptation
Western Alliance Must Hold
Washington should separate three missions that are too often blurred together:
The first is maritime security: keeping the Strait of Hormuz open enough that Iran cannot normalize coercive control of global shipping.
The second is sanctions enforcement: tightening visibility into Russian oil transport, insurance, ownership, and payment channels.
The third is public financial warning: making clear to ordinary investors that viral oil-backed tokens are not sovereign instruments unless verified by law, audited reserves, identifiable issuers, and recognized regulators.
The United States should also treat blockchain analytics as a national-security function, not just a financial-crimes specialty. If Russia is using cryptocurrency to support oil trade, the issue belongs not only to the Treasury Department but also to intelligence agencies, energy analysts, sanctions lawyers, maritime authorities, and allied financial regulators.
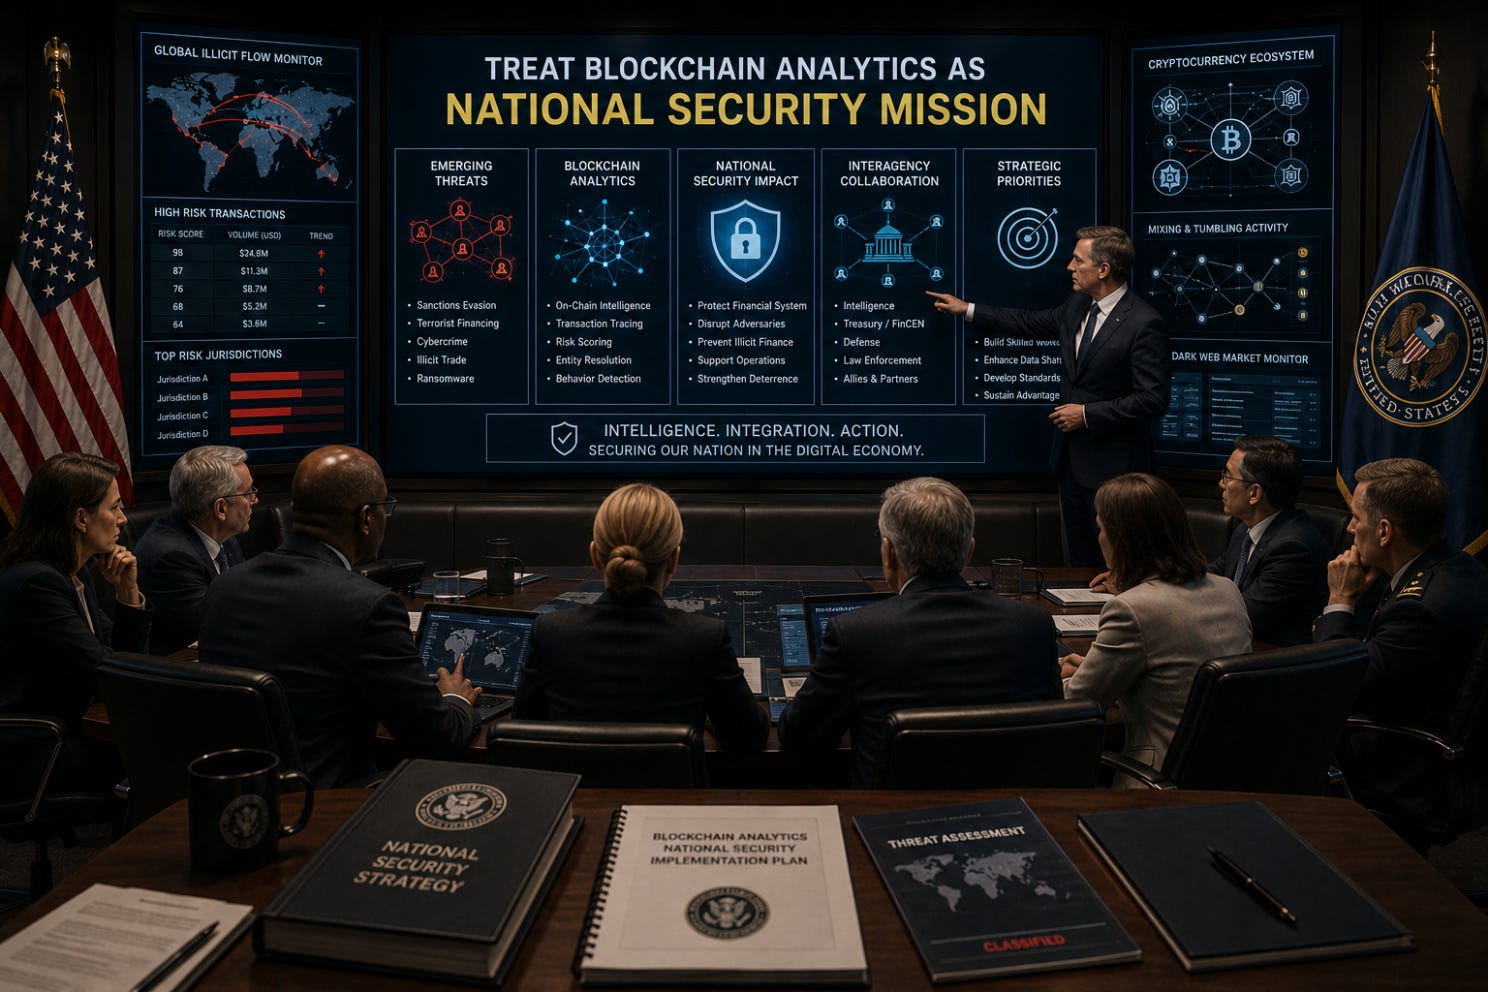
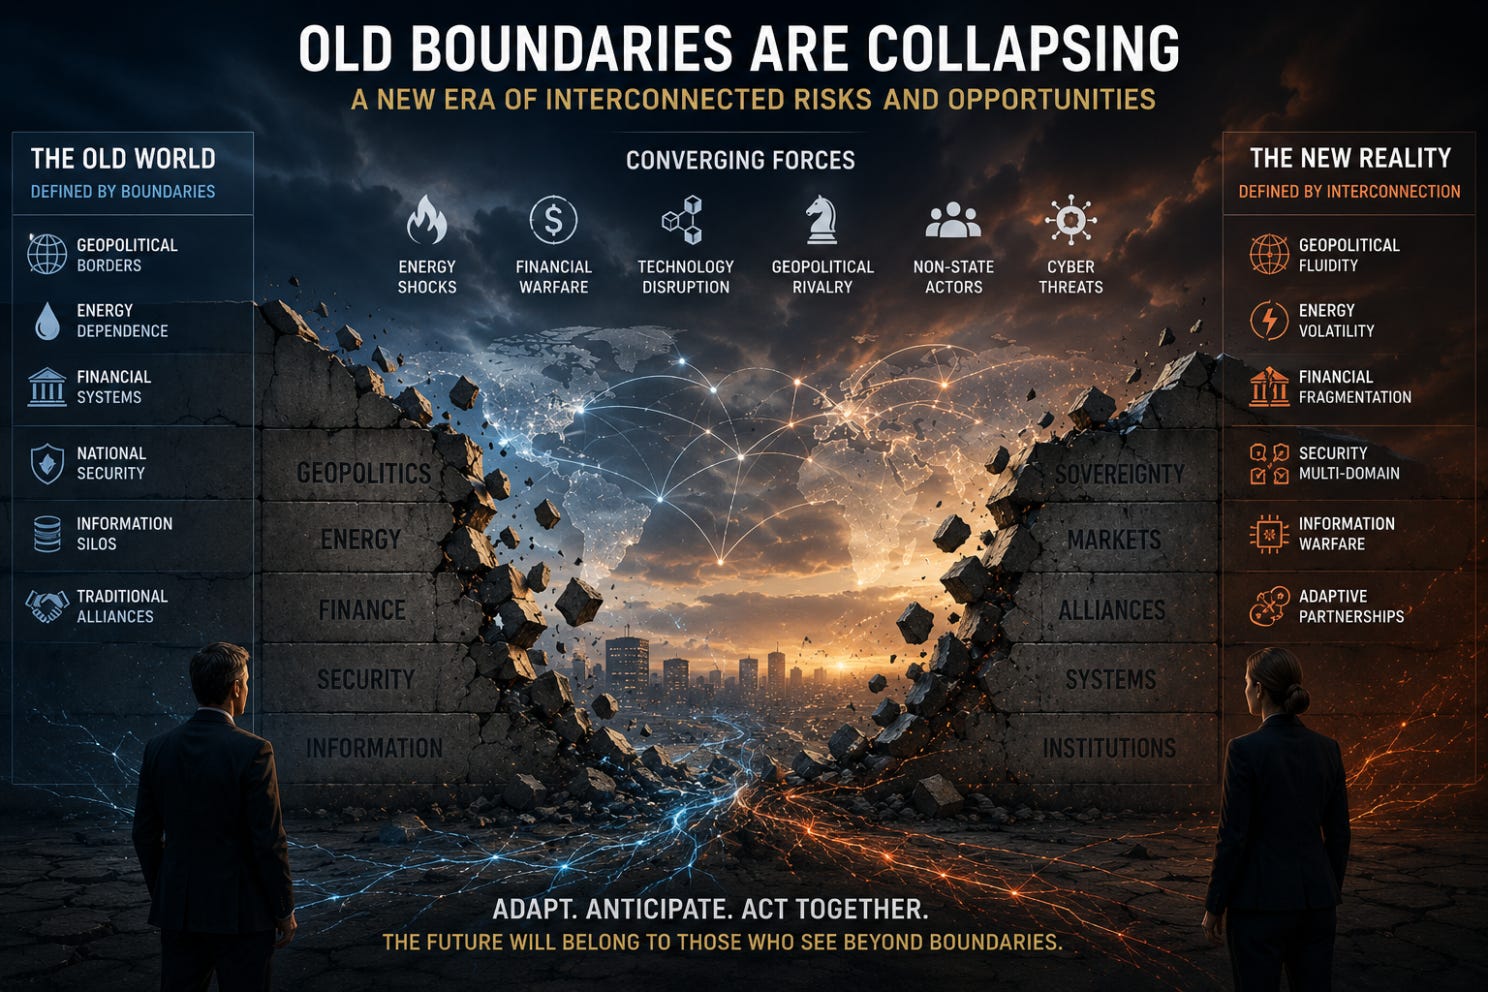
The deeper issue is that the old boundaries are collapsing:
Oil is no longer just a commodity. It is a sanctions target, a naval problem, a domestic inflation trigger, a Russian budget line, a blockchain settlement challenge, and a battlefield narrative.
That is why a Persian Gulf flare-up, a Russian tax calculation, a crypto token on Solana, and a fake Reuters screenshots all over the internetr may belong in the same strategic picture.