
For more than half a century, the most powerful instrument of American statecraft has not been military force alone. It has been the financial architecture surrounding the U.S. dollar.
Global energy markets, sovereign debt flows, and international trade settlement have all operated inside a structure that quietly reinforced the central role of the American currency. That system emerged after the collapse of the Bretton Woods order in 1971.
Today it still dominates global finance, but new geopolitical and financial pressures are beginning to test its long‑term durability.
Officials in Washington and allied capitals increasingly describe the situation not as an imminent collapse of dollar dominance but as the slow appearance of alternatives. Rival powers are probing the edges of the monetary order built by the United States during the 1970s.
At the same time, sanctioned states such as Iran and Russia have strong incentives to experiment with non‑dollar financial channels. The intersection of these trends is quietly reshaping the strategic environment surrounding the current Iran crisis.
Understanding the stakes requires returning to the moment the modern system was built.
In 1971 President Richard Nixon ended the convertibility of the U.S. dollar into gold, effectively dismantling the Bretton Woods monetary system created after World War II.
Under Bretton Woods, the dollar had been tied to gold and other currencies were tied to the dollar. When the gold link ended, the United States faced a fundamental question: what would sustain global demand for dollars?
The answer emerged through diplomacy led by National Security Advisor and later Secretary of State Henry Kissinger. Following the 1973 Arab oil embargo, Washington negotiated a strategic arrangement with Saudi Arabia.
Under the framework developed in 1974, the United States would provide security guarantees, military cooperation, and large arms transfers to the Saudi kingdom. In return, Saudi oil exports would be priced exclusively in U.S. dollars and Saudi oil revenues would be reinvested into American financial markets, particularly U.S. Treasury securities.
The Endless Feedback Loop of Debt
The arrangement created a powerful financial feedback loop that quietly reinforced American global power. Because oil was priced in dollars, every nation that needed energy first had to acquire U.S. currency.
That structural demand ensured a constant global market for dollars regardless of the underlying U.S. trade balance.
Oil exporters, led by Saudi Arabia, accumulated vast dollar surpluses from these transactions. Rather than holding those revenues in idle reserves, they recycled them back into the American financial system, particularly through purchases of U.S. Treasury securities and other dollar-denominated assets.
The result was a self-reinforcing closed loop: the United States could expand its money supply and issue debt to finance domestic spending, foreign aid, and military operations, while global energy demand ensured continued demand for dollars and foreign reinvestment into U.S. government debt.
This cycle allowed Washington to fund large deficits (and Wars) at relatively low cost, sustain extensive overseas security commitments, and exercise extraordinary influence over global financial flows, making the dollar not merely a currency but a central instrument of geopolitical power.
Fifty Year of this loop
In 1975 the entire U.S. national debt was about Five-Hundred Billion. By 2026 it is approaching $40 trillion.
That represents one of the largest fiscal expansions in modern economic history.
Reporting years later confirmed elements of the arrangement when previously classified financial agreements were examined through Freedom of Information Act requests and archival disclosures.
Bloomberg reporting on U.S.–Saudi financial arrangements: https://www.bloomberg.com/news/articles/2016-05-31/the-secret-deal-that-made-saudi-arabia-the-world-s-biggest-investor
The arrangement soon expanded across the Organization of Petroleum Exporting Countries (OPEC). Because oil is the most traded commodity in the world, every country that needed energy now needed dollars to buy it. Oil exporters accumulated dollar surpluses and reinvested those surpluses into Western financial markets.
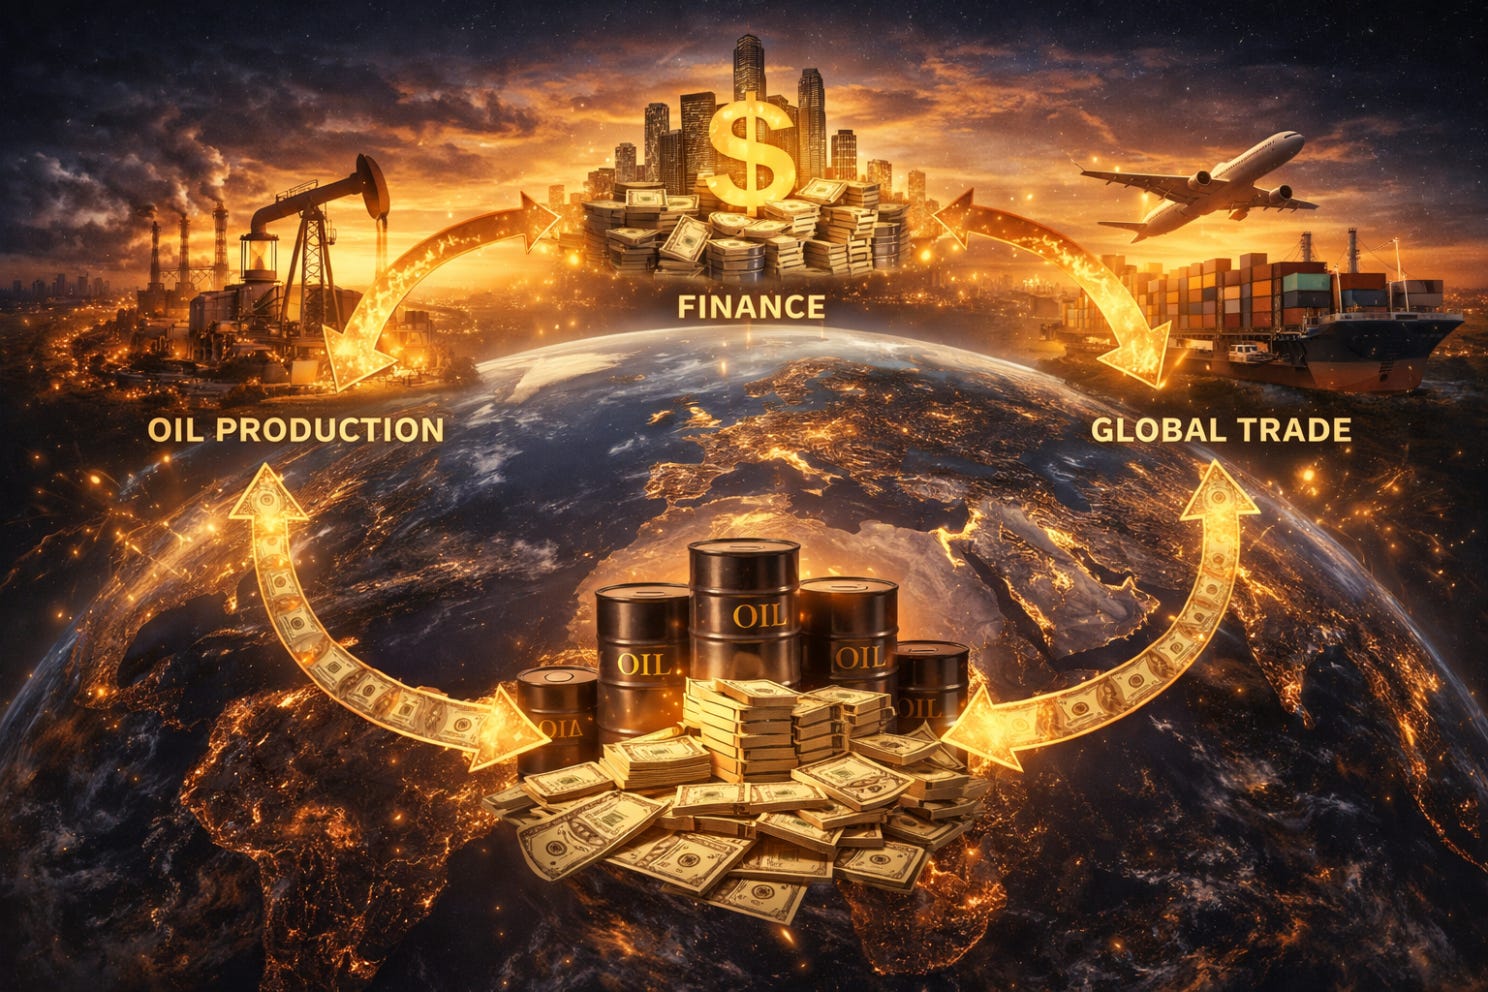
Economists later called the process “petrodollar recycling.”
Energy importers bought dollars to purchase oil. Oil exporters accumulated dollars and reinvested them in U.S. Treasury securities. The cycle strengthened global demand for the dollar and helped finance American deficits at relatively low cost.
According to the International Monetary Fund (IMF) and the Bank for International Settlements (BIS), the dollar still accounts for roughly sixty percent of global foreign‑exchange reserves and the majority of international trade settlement:
International Monetary Fund reserve statistics: https://www.imf.org/en/Data
Bank for International Settlements global currency statistics: https://www.bis.org/statistics
The Deal That Funded 50 Years of Wars
Yet the structure that supported the petrodollar system is beginning to evolve.
BRICS
The most visible pressure comes from the expanding coordination among countries grouped under the BRICS framework: Brazil, Russia, India, China, and South Africa. The bloc has recently expanded to include additional energy producers and regional powers including Saudi Arabia, Iran, and the United Arab Emirates, and the Republic of Indonesia.
BRICS DOLLAR
China has been the most systematic in promoting alternatives to dollar settlement. Beijing launched yuan‑denominated oil futures contracts through the Shanghai International Energy Exchange and has encouraged major energy exporters to accept renminbi payments.
Shanghai International Energy Exchange crude oil futures:
https://www.ine.cn
China has also built a parallel financial infrastructure known as the Cross‑Border Interbank Payment System (CIPS), which provides an alternative channel for international financial transfers outside the traditional SWIFT system.
People’s Bank of China overview of CIPS:
https://www.cips.com.cn
Russia has moved a significant portion of its energy exports into yuan settlement following Western sanctions imposed after the invasion of Ukraine. India has experimented with rupee‑denominated settlement mechanisms for bilateral trade.
Even traditional U.S. allies have begun exploring limited diversification strategies designed to reduce dependence on a single currency channel.
Japan’s Big Play
Japan is now considering an unusual strategy linking oil markets directly to currency policy. Instead of only intervening in foreign exchange markets, Tokyo is discussing using its massive foreign-exchange reserves to intervene in oil futures markets to influence global oil prices.
The logic is straightforward:
Rising oil prices increase global demand for U.S. dollars, because most oil is still priced in dollars.
That strengthens the dollar and weakens the Japanese yen.
By pushing oil prices down through futures trades, Japan hopes to reduce dollar demand and stabilize its currency.
Japanese officials have warned that oil-driven speculation is distorting currency markets and have signaled that the government is prepared to act if necessary.
Why This Matters Strategically
Japan’s move reflects a deeper shift in how governments view energy markets as a tool of financial statecraft.
These moves remain modest compared with the scale of global dollar use. But strategic systems rarely collapse suddenly. They change gradually as alternatives appear at the margins.
The Iran crisis highlights how financial and geopolitical pressures can reinforce one another.
For decades Iran has attempted to bypass the dollar system due to Western sanctions targeting Iranian banks and oil exports. Iranian oil now moves through complex networks involving China, regional intermediaries, and shadow trading structures designed to avoid Western financial oversight.
Energy analysts say the total volume of these trades remains relatively small compared with global energy markets. Yet the strategic importance lies in the precedent. Iran and its partners have demonstrated that energy trade can occur outside the traditional dollar system when geopolitical pressure forces financial innovation.
This reality becomes more significant when combined with the broader geopolitical landscape:
China is now the world’s largest importer of oil.
Russia remains one of the largest exporters of energy to Asia.
Iran occupies a strategic position near the Strait of Hormuz, the maritime chokepoint through which roughly twenty percent of global oil supply flows.
U.S. Energy Information Administration Strait of Hormuz analysis: https://www.eia.gov/international/analysis/regions-of-interest/Strait_of_Hormuz
In such an environment, financial experimentation and strategic rivalry reinforce each other. Some intelligence analysts argue that Iran’s leverage in the current crisis lies not only in missile forces or proxy networks but also in its ability to influence the stability of energy flows that underpin the global financial system.
The United States therefore faces a strategic dilemma.
Financial sanctions and dollar‑based leverage have become central tools of American foreign policy. They are powerful precisely because global commerce depends heavily on dollar clearing networks. But the broader and more frequent the use of those tools becomes, the stronger the incentive for other nations to construct alternative financial channels.
Officials in allied governments privately acknowledge this tension. Sanctions can impose immediate costs on adversaries, yet they may also accelerate long‑term diversification away from the dollar system.
The outcome will depend on the interaction between geopolitics, energy markets, and financial innovation.
If the current crisis involving Iran disrupts energy supply routes, global markets may lean even more heavily on dollar‑denominated transactions because U.S. financial markets remain the most liquid and trusted in the world.
Energy crises historically strengthen demand for the dominant reserve currency.
But another scenario is possible. If major powers respond by strengthening non‑dollar settlement mechanisms—particularly among BRICS members—the global financial system could gradually fragment into multiple currency networks.
In that environment the dollar would remain powerful but less exclusive.
Senior policymakers increasingly describe the situation as a long strategic competition rather than a sudden monetary revolution.
The durability of the dollar system will depend on the strength of U.S. alliances, the credibility of American economic governance, and the discipline with which Washington applies financial coercion.
The petrodollar architecture was never purely economic. It rested on security guarantees, stable energy flows, and political trust.
If those pillars weaken, the financial structure built upon them will evolve.
For now the dollar remains the foundation of the international system.
But history suggests that monetary orders rarely collapse overnight. They shift gradually, often at the margins, until cumulative adjustments reshape the system itself.
The strategic challenge for Washington is to recognize those shifts early and manage them carefully.
As the Prussian strategist Carl von Clausewitz famously observed, “war is the continuation of politics by other means.” In the twenty-first century that insight requires an important update.
Carl von Clausewitz served as a Prussian general during the Napoleonic Wars and later became one of the most influential military thinkers in history.
Carl von Clausewitz (1780-1831)
Military confrontation has not disappeared, but it now operates alongside an expanding arena of economic and financial conflict.
Currency settlement systems, energy pricing mechanisms, sanctions regimes, and payment infrastructure have become instruments of geopolitical competition every bit as consequential as missiles or carrier strike groups.
The quiet financial contest surrounding the dollar, BRICS experimentation, and Iran’s sanctions-resistance networks illustrates this shift clearly.
What is unfolding is not a traditional battlefield struggle but a strategic contest over the architecture of global commerce itself. If Clausewitz viewed war as politics conducted through violence, today’s geopolitical reality increasingly reflects politics conducted through financial systems, energy markets, and technological infrastructure.
The outcome will not be determined in a single crisis or currency announcement but through a long process of institutional competition—one in which credibility, alliances, and economic governance may ultimately prove as decisive as military strength.
Super great article! At last, a recognition of how the world really works, and how the US set it up that way. Now, connect the dots and see how it explains our Middle East military adventures. I’m waiting for that one.
You are a true gem in geopolitical analysis.
Keep up the good work!